Tuesday, October 11, 2011

Aeropostale (NYSE:ARO): Actionable Call Alert!

Jefferies & Co star retail analyst Randal Konik is making a potentially very significant call in Aeropostale (NYSE:ARO) upgrading the teen retailer to Buy from Hold with a $20 price target (prev. $12).

The call is titled 'Upgrading to Buy: We've Seen This Movie Before & We Like the Ending'

Konik highlights 5 reasons why investors should be buying ARO shares here. Most importantly he believes ARO is currently in a similar position to Abercrombie & Fitch (ANF, $67.98, Buy) when the stock reached trough fundamentals back in early 2009. ANF has since seen a turnaround in its business and its stock increase ~165% (vs. S&P up 35%).


THE DETAILS:

Fundamentals Should Improve. In 2011 ARO has seen slowing sales momentum, loss of market share and margin compression as the company lapped peak fundamentals and faced a tough competitive environment. However, we believe the company is now near trough fundamentals and will begin to see improvement in coming quarters as inventories come more in line with sales trends, ARO laps easier comps and some fashion issues are fixed.

We believe ARO margins are currently near trough levels at an estimated ~4% this year, and we expect margins will begin to improve in FY’13 for the following reasons:

1) ARO brings inventory more in line with sales.
2) Comps begin to improve as ARO cycles past easier compares.
3) ARO aims to correct some mistakes in the women’s business
through an improved color palette and fashion.
4) Sourcing cost inflation abates

This Company Is Not Going Away. We continue to believe that ARO's business model is intact and that the company will again prove to be a key teen brand. Further the company's balance sheet and cash flow remain strong despite the tough fundamentals today.

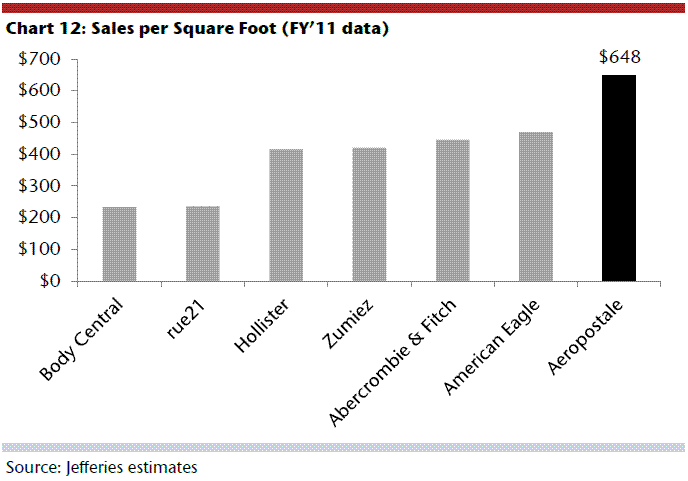
Aeropostale has some of the most productive stores in the specialty retail space. While the sales per square foot metric will be down this year vs. LY, we believe this very high level of productivity shows that the stores are in a cyclical slump, not a secular one.

Aeropostale currently has 5.2m fans on its Facebook page

Sentiment is Already Very Negative. ARO has significantly reduced its earnings outlook this year and the stock is down over 50% YTD (vs. S&P down 5%). Further, sentiment is very negative with short interest near 20% of the float and very few buy ratings on the stock.

Back in early 2009, investor sentiment around ANF was particularly negative. This is illustrated by the high short interest and low number buy ratings among sell side analysts. ANF’s short interest as a percentage of the float peaked at ~19% in April 2009 as investors viewed the brand as largely dead and the company’s long term story broken. Analyst sentiment was also quite negative for ANF with less than 30% buy ratings, ~60% hold ratings and over 10% sell ratings.


What We Expect Will Happen at ARO
Investor sentiment around ARO has become increasingly negative this year following multiple downward earnings revisions and slowing fundamentals. We believe many investors view the ARO story as broken (much like they did for ANF in 2009).

This is evidenced by ARO’s short interest as a percentage of the float which has been increasing and is currently at 16%. Analyst sentiment is also negative for ARO with only 20% buy ratings, over 60% hold ratings and almost 15% sell ratings.

Among our coverage universe, ARO’s buy ratio (defined as the number of buy ratings as a percentage of total ratings) is one of the lowest at 21%. This compares to the average Buy ratio among our group of over 50%.


Risk/Reward Now Compelling to the Upside. With the stock one of the worst performing in our coverage universe, we now see little downside risk and meaningful upside in the coming months as margins and top line begin to recover. As such, we view risk/reward as very attractive at current levels.


Notablecalls: I'm calling this one Actionable Call Alert.

Here are my reasons:

1) Konik has done a very good job in ARO. He cut the name to Underperform on Jan 3 when the stock was trading around $25. Straight down. He kept pounding it all the way, ending with a $12 price target in August.

He upgraded ARO to a Hold on August 16 saying ARO had played out to his thesis with significant top-line and margin erosion YTD.

2) Konik compares ARO to ANF in 2009. A wild ride. But he was right. So right.

3) The call reads well and short interest stands at 18% of float. Sentiment is uber-negative so it won't take much to light up the stock.


I don't see this thing stopping before it hits $13 in the n-t. I suggest you don't chase it too high in the pre market and watch for any pullbacks after open to buy.

Longer term? A potential double or more.

(PS: Posting this around open)

Wednesday, October 05, 2011

Notable Calls Network (NCN): AM, SFLY & CSCO

We have caught some interesting (and profitable!) situations at Notable Calls Network (NCN) in the past couple of days:


1) Shutterfly (NASDAQ:SFLY), American Greeting (NYSE:AM)

Apple announced yesterday at their iPhone 4GS event that they will be releasing an app for iOS devices, where users can create and mail 1 to 1 greeting cards.

- Around 1:28 PM ET a particularly sharp & knowledgeable NCN member hit me with the following remarks:

New iPhone, iPad app called "Cards" allows you to make cards to send to people. American Greetings (NYSE:AM) getting hit on this, Shutterfly (NASDAQ:SFLY) also. "SFLY might get killed on this, " he added.

I quickly blasted the comments to NCN. Here what's happened:


American Greetings (NYSE:AM) went from $18 to as low as $16 (2 pts)

Shutterfly (NASDAQ:SFLY) went from $39 to as low as $33.50 (5.5 pts)

Both trades had ample size to be taken.

- We also caught a couple of analyst defends in SFLY, as around 1:55 PM ET Morgan Keegan was out defense of the name saying Apple has been in the photo market for years with iLife and its latest app does not appear to challenge Shutterfly in events and occasions, design choice, or even on price. (Marked green on the chart)

As you can see that also delivered for us.


2) Cisco Systems (NASDAQ:CSCO)

- Around 10:33 AM ET a hedge fund manager primaly focused on technology sector pinged me with the following snippet:

WASHINGTON (Dow Jones)--A bipartisan pair of senators plans to introduce on Thursday a bill proposing a tax break for U.S. companies that bring home foreign profits.

"= CSCO, MSFT, AAPL," he added.

This made perfect sense. Cisco (NASDAQ:CSCO) buybacks! Offshore cash!

- Here's what happened: $0.50 move in CSCO.


Later a NCN member told me he got $0.20 on 150,000 shares from the call. That's $30,000 profit in one trade.

These are the things that make me smile.


This is how Notable Calls Network (NCN) works - sharing the flow. We catch them every day.

Want to be part of NCN?

It's easy. Just shoot me a brief email that includes a short description of yourself and your AOL nickname.

Please do note that contacts via IM are limited to people with:

- 3+ years of trading experience

- Access to quality research/analyst commentary

- Ability to generate and share (intraday) trading calls

I will not accept contacts from purely technically oriented traders, penny stock fans or people who have less than 3 years of experience in the field.

Monday, October 03, 2011

Priceline.com (NASDAQ:PCLN): Upgrade to Overweight at Morgan Stanley

Morgan Stanley's Internet team is taking a bold step and upgrading Priceline.com (NASDAQ:PCLN) to Overweight from Equal-Weight while establishing $650 price target.

Firm believes the market is incorrectly assuming that Booking.com has limited growth potential in Europe and APAC due to escalating competition and macro weakness, providing investors with a compelling buying opportunity. Morgan Stanley is raising their estimates above consensus.

The details (in short):

European competitive advantage + secular tailwinds outweigh cyclical risk: Based on our checks, Booking.com still provides the best value proposition to European hotels with the lowest commission rates and largest customer reach relative to competition. Additionally, Booking.com is well positioned to benefit from the ongoing offline-to-online shift in European hotel bookings, which in our mind, outweighs cyclical risk. We model Booking.com increasing its share of the European hotel market from ~8% in 2010 to ~18% in 2015.


Asia Pacific: a new opportunity: Booking.com brings a unique value proposition to Asian hotels with its large European customer base, which local online travel agencies are unable to provide. Additionally, the recent appointment of Darren Huston as CEO of Booking.com (former CEO of MSFT Japan) brings valuable knowledge on effective APAC marketing strategies. We are not modeling Priceline dominating the APAC market, but rather continuing its current growth trajectory, growing market share from ~1% in 2010 to ~5% in 2015.

Valuation: At current price levels, Priceline trades at 11.5x 2012e EV / EBITDA, a discount to Ctrip at 15x and Make My Trip at 30x. We believe Priceline’s multiple will expand closer to its Asian counterparts, as Booking.com gains market share in Europe and Asia Pacific

Notablecalls: Big mo-mo names have been under pressure past days, possibly because of JAT liquidations. As one of the top guys on Notable Calls Network (NCN) notes PCLN has fallen too much too fast and is now getting a size upgrade & target.

PCLN is squeeze material. The market needs to cooperate of course.

Same goes for Netflix (NASDAQ:NFLX) which is getting +ve Research Tactical Idea (RTI) from Morgan Stanley.

"The TRIN closed at 3.89 which is a bit panicky, I think we can get a down to up on the day at some point", another trader notes.

Wednesday, September 28, 2011

Netflix (NASDAQ:NFLX): Subscriber Churn Stabilizing - Piper Jaffray

Piper Jaffray is out with some interesting comments on Netflix (NASDAQ:NFLX) this morning noting their 2nd Subscriber Survey shows churn stabilizing in late Sept.

- As a follow-up to their 350 subscriber survey in mid-August, they firm recently surveyed 250 Netflix subs to gauge subscriber behavior. The outcome of the survey, conducted on 9/19 (after the apology email from CEO Reed Hastings to subscribers announcing the Qwikster spin-off), was similar to the mid-Aug survey; however, the number of subs that expect to quit the service is now down to 10% from 15% previously.Piper believes their survey shows that subscriber cancellations are stabilizing after being higher than expected for the majority of Q3. While they continue to expect elevated churn over the next few quarters, the risk of a mass exodus appears to be moderating following their mid-Sept. survey.

Firm reiterates Overweight & $300 PT.

Here's the gist of it:


Couple of points:

1) People planning to quit Netflix is down to 10%.

2) People planning to move to Redbox is down from 56% to 42%.


NO MASS EXODUS.

Notablecalls: Why this is important? I hate to say it but if you look at Olson's mid-August survey closely enough, you will know why. The survey rather cleraly highlighted people's discontent towards the price hikes. It showed people planning to leave NFLX and join CSTR.

I remember arguing about it with a guy sitting next to me at the desk. We both knew the info was material but we didn't have the guts to go against the tape and short the name. What happened was NFLX went down and CSTR went up big. We looked (and felt!) like two putzes. That was August 17 and NFLX was trading around $240+.

Now we have the stock down $100+ pts and Olsen is saying monthly churn won't be as bad as the initial read suggested.

Will it be enough to produce a bounce in NFLX?

I don't know. The chart looks bad & AMZN is about to reveal their streaming service today @ 10:00 AM ET.

Gotta play this one by ear today. Could see $10+ upside, if people really pick it up.

Monday, September 26, 2011

Netflix (NASDAQ:NFLX): Upgrade to Buy at Merriman

Merriman's Eric Wold is upgrading his rating on Netflix (NASDAQ:NFLX) to Buy from Hold with a $155-175 valuation range.

The analyst notes they downgraded NFLX to Neutral on July 6, the shares have dropped 55% vs. a 15% decline in the S&P 500. At this point, they believe their near-term concerns are more than reflected in the valuation - which no longer gives Netflix credit for its industry positioning and long-term potential. Firm is upgrading NFLX to Buy in spite of the near-term headwinds as their downside 2012 EPS analysis still shows solid growth potential over 2011. They are making no changes to their estimates at this time and see upside to $155-175 using a P/E of 25-28x.

The details (in short):

Downside 2012 EPS scenario still shows growth. In our downside analysis for 2012, we come up with a potential range of $4.49-5.95. The midpoint of $5.22 still represents a solid 21% growth over our current 2011 EPS estimate of $4.33. Given the consensus range of $5.38-9.69, we believe it is apparent that there are numerous drivers that could push results either way. However, we believe our analysis shows a realistic downside scenario that should give investors comfort in Netflix's still strong industry position - and that 2012 solely represents a potential pause before strong margin/EPS growth resumes in 2013.

Starz savings could offset earnings pressures. During 2012 we see three main earnings headwinds that could potentially push EPS below current expectations: 1) migration of DVD-only subscribers; 2) international launch operating losses; and 3) competition causing upward pressure on SAC. However, we believe the $250M in 2012 content savings from the Starz cancellation gives management some wiggle room should they not find
alternative content (or choose not to spend the surplus).

Two biggest drivers firmly in control. At this point, we believe it is increasingly clear that the two biggest earnings drivers in 2012 - marketing and content spend - are firmly in management's control. This is key in that should spending on those two areas not generate positive results, we believe management could easily pull back the reins to maintain solid profitability by catering to existing subscribers instead of pushing to add new ones.

Division split more of a content decision. We understand some believe management's decision to split the streaming and DVD divisions is to better position the streaming division for a sale to a larger competitor. However, even though this may help to improve the sum-of-the-parts valuation multiples afforded by investors, we believe the larger driver was to aid in content negotiations with a smaller number of streaming subscribers driving cost discussions (i.e., lowering the cost) vs. the entire pie (including DVD-only subscribers).

Near-term risks remain in spite of upgrade. Our decision to upgrade to Buy from Neutral today is not based on any improving outlook for the near-term and continue to see risk in subscriber trends through yearend. Furthermore, based on our EPS analysis, we believe there is a morethan- likely chance that 2012 consensus estimates (and possibly our belowconsensus estimate) may need to be reduced. Nevertheless, we believe NFLX shares already more than reflect these risks and should our downside analysis prove aggressive, we could see the shares rebound sharply in 2012 on an improved growth/margin outlook.

Notablecalls: Eric Wold nailed it on July 6th when he downgraded NFLX to a Hold from Buy saying the co would be entering a period of restrained operating margins.

He played the name so well on the way up and looks like he played it even better on the way down. Some of this performance can surely be attributed to blind luck (at least ONE of the analysts among many should get it right) but I do like his style. As was the case with the downgrade, Wold is not being pushy but rather pointing out things may not be as bad as the market suggests. According to Wold, 2012 may bring a sharp bounce-back.

Another thing that caught my eye this morning is that the analyst community is not overly excited about the DISH movie streaming package. It appears to cost more and have way less content that the NFLX offering. So n-t overhang lifted there.

(Now we can all go on and start worrying about what AMZN will unveil in 2 days).

Anyway, I wouldn't be surprised to see the stock lift following the Merriman upgrade. Hopefully another brilliant call for Eric Wold.

Give Kudos when it's due. I do!

Wednesday, September 21, 2011

Autodesk (NASDAQ:ADSK): Actionable Call Alert!

J.P. Morgan's Software team is flip-flopping some names under their coverage this morning:

- ADSK, ROVI get upgraded to Overweight while VRSN and DOX are cut to Neutral.

I want to focus on Autodesk (NASDAQ:ADSK). JPM is upgrading the name to Overweight from Neutral with a $40 price target.

According to the firm, ADSK is one of the best franchises in their coverage. It has a substantial market share in a couple of key industry segments (AEC and Infrastructure) and is very competitive in manufacturing design software. The business is highly cyclical and they missed two other good entry points during the downturn in February of 2009 and July of 2010. They believe investors should take advantage of the cyclical pullbacks to build positions in what they consider a high quality software franchise. In addition, this next cycle has the potential added benefit of a move into product suites, a strategy that has helped companies like Adobe breathe large new growth opportunities into its business and something they think could underpin at least a 12% top line CAGR for ADSK over the next five years.


The details (in short):

Move to suites should provide at least 12% CAGR over 5 year horizon
Over the years we have watched a couple of software companies move from offering just point products to bundles of products to ultimately product suites that tightly integrate solutions and at attractive combined pricing. The first most notable company to follow this strategy is Microsoft with the Office suite, but we believe the best comparison for Autodesk is Adobe and its move to suites.

We went back and looked at the penetration rates of suites for Adobe and the impact on revenue and applied this to Autodesk. Result is that we see a base of 12% revenue CAGR over the next five years. Reason we say a base is that we lack perfect insight into the user base at Autodesk for products like Revit where we think there is potential to add another 3-4% to the revenue growth. But we think this view of Autodesk suite opportunity is very interesting given it is based on another software company with a very loyal customer base in Adobe.

Recent market action sets a range in our mind where the stock we think offers $12 of upside if the economy improves against the risk of $4-5 of downside if the economy worsens.

Notablecalls: JPM picked a (very) good day to upgrade ADSK as the August Architectural Billings Index (ABI) published last night showed a surprising jump.

The Architectural Billings Index (ABI) is a survey by the American Institute of Architects (AIA) and is viewed as a leading indicator of nonresidential construction activity. A score of 50 or above indicates an increase in billings. The AIA believes the index has a correlation with nonresidential construction spending 9-12 months into the future.

ADSK is one of the leading providers of software used by architects and engineers. If AutoCAD means anything to you, you're on the right tracks.

In a bit of a shocker, the ABI spiked higher in Aug. The index jumped 6.3 pts from 45.1 to 51.4. That's the biggest m/m change in 5 years (Aug '06). "Based on the poor economic conditions over the last several months, this turnaround in demand for design services is a surprise," said AIA Chief Economist, Kermit Baker, PhD, Hon. AIA. "Many firms are still struggling, and continue to report that clients are having difficulty getting financing for viable projects, but it's possible we've reached the bottom of the down cycle."

Here's an illustration from Morgan Stanley explaining why ADSK shareholders track the ABI index:

So there you have it. JPM upgrade and an explosive move in the ABI index should get ADSK moving. The stock should trade towards $30 level in the n-t, possibly surpassing it if the tape holds.

Let's see how it goes. I'm going to call this one Actionable Call Alert!

(PS: I'm posting this right around open)

Monday, September 19, 2011

Mckesson (NYSE:MCK): Rapid Profit Expansion Expected Near Term; Upgrading Cardinal and McKesson to BUY - Citigroup

Citigroup's Health Care Distribution & Technology is making a fairly big call upgrading both Mckesson (NYSE:MCK) and Cardinal Health (NYSE:CAH) to Buy from Hold.

- Mckesson is added to Citi's Top Picks Live (TPL) list with a $101 price target (up from $90).

New Generic Introductions Should Provide Outsized Profits in C2012 – In the report, Citi examines the upcoming branded to generics wave set to impact the drug distributors beginning in 2011 though the end of 2015. They look at 100+ drugs that currently generate about $90 billion in revenue and their impact on wholesaler profits and margins. Firm estimates that the branded to generic conversion wave will lead to outsized profits and sustainable higher margins for the wholesalers.

The details:

Industry Top Lines Should Begin to Shrink in C2012 – One dynamic of the branded to generic drug conversion cycle is that wholesaler top lines should begin to decrease in 2012. Single source generic drugs can sell at about half the reference drug price and we believe many large customers will buy these generics direct, leading to significant leakage out of the wholesaling channel. We estimate that wholesaler revenue levels could shrink 2% to 8% in the 2012/2013 time period on a reported basis and 5% to 10% on a like for like basis, excluding acquisitions and nondrug distribution businesses.

But Gross Profits Should Expand on Mix – Within the customer base that buys generics from the wholesalers, generic drugs can be 3x to 20x as profitable as their branded drug counterparts. This should lead to both absolute higher profit levels and higher margins for the wholesalers reflecting the shifting mix to generics as a higher percentage of total drugs sold. About 50% of generic drugs dispensed in the U.S. are bought by retailers (or mail order) directly from the manufacturer, meaning the wholesalers will share the generic profit opportunity with other parts of the channel.

Difficult Comparisons Begin in 2H-2013 – We believe an underappreciated dynamic of the branded to generic conversion is the level of profits contributed by single or dual source generics, compared to multisource generics. These limited source generics can produce dollar profit levels that are 3-4x the multisource equivalent. So as many of these drugs move through their life cycles to multisource competition, the gross profit contribution from these drugs will decrease substantially. This should create difficult comparisons in 2013, as drugs including Lipitor, Lexapro, Seroquel, Plavix and Singular should all see multisource generic competition.

Upgrading Cardinal Health and McKesson to Buy, Maintain Hold on AmerisourceBergen – Our revisions make us at or near the Street High estimates on both companies for their F2012 and F2013, implying significant positive revisions which should lead to multiple expansion from current levels. Our target price on CAH goes to $51 from $44 and our target price on MCK is now $101 from $90.

Notablecalls: My poison of choice here would be MCK, as the name is added to the TPL with a very nice $101 price target.

What really makes the call interesting are the catalysts:

- Lipitor is going to launch in Nov 2011, that's 45 days from here. It's the largest drug in the world by sales which should create some excitement among investors.

- McKesson benefits when UNH brings PBM business in house. Of course that won't happen til 2013.

It's a 54 pg. note so the good people at Citi have put work into the subject. The sales will be making a lot of calls today pushing MCK & CAH to clients. Especially MCK since it was added to the Top Picks Live list. Nice defensive name too.

I expect a nice up day for MCK. $78+?

(Posting this after open)

Thursday, September 15, 2011

Central European Distribution (NASDAQ:CEDC): Merger Talks with Anisimov, Rosspirtprom? - Citi

Citigroup's Beverages team is out with some interesting comments on Central European Distribution (NASDAQ:CEDC) noting Russian newspaper Kommersant has a front-page article this morning saying that CEDC is in merger talks with Vasiliy Anisimov and Rosspirtprom to combine their respective Russian assets into a single organisation.

According to the article, the discussion is around Anisimov receiving a 20% stake in CEDC in exchange for his various Russian alcohol assets (86% of Moscow vodka factory Kristal, VEDK distribution business with the exclusive distribution contract on the popular brand “Putinka”). A third party in the deal is reportedly Rosspirtprom, under whose umbrella the combined Russian assets would be managed. According to data in Kommersant, this would potentially increase CEDC’s market share from 14% to ~21%. None of the parties involved have commented on the press report.

According to Citi, this is not the first public speculation over a deal for CEDC and may not be the last given the difficult position the company finds itself in due to a combination of an underperforming operational business and a stretched balance sheet. Previously the stock has reacted positively to press speculation of acquisition (press reports of a $17/share offer by Roman Abramovich in May that an Abramovich spokesman later denied) or to investors building a large stake (Mark Kaufmann issued an SEC filing recently saying he had acquired 9.6% of the company). Last week CEDC’s Board of Directors adopted a “poison pill” giving them power to significantly dilute any potential unfriendly buyer, which could be taken as a sign the BoD has other plans for regaining investor confidence.

While it would be too early to make a fundamental analysis based on the details available, Citi's initial impression is that if such a deal is under consideration, they see more positives than negatives.

– First, this may solve CEDC’s Russian performance issues through the return of key managers who built the core Russian Alcohol Group (RAG) which CEDC acquired in 2008 (but who now, according to Kommersant, work for VEDK and Rosspirtprom). While they do not know the two managers in question they believe this change would be taken positively by the market considering the visible success of initially building the RAG business (and subsequent decline once these managers left).

– Second, the combination of improved consolidated cash flows and the return of these key managers would in our view significantly improve the company’s chances of meeting a major re-financing challenge in March 2013 when $300mln in convertible bonds comes due.

Notablecalls: CEDC has been beaten to bits following 3 disappointing quarters and I suspect that any change in leadership and operations will be welcomed by investors.

Rememeber, this was a $26 stock mere 8 months ago.

Gaining 28% market share in the Russian Vodka market? That's fairly significant. #1 player.

CEDC produced a 50%+ move on August 29 following the Kaufmann stake news which means it's a mover.

I'm guessing CEDC will see $7.50-8.00+ on this.

Here's the Kommersant piece, use Google translate.

Monday, September 12, 2011

Notable Calls on Twitter

Gentlemen,

I'm going to have another go with this Twitter thing. It didn't feel right the first time around but let's see how it works out this time. Just to give a little taste of what's going on at the Notable Calls Network (NCN) intraday.

http://twitter.com/#!/thenotablecalls


Good luck,

NC

Tuesday, September 06, 2011

SodaStream International (NASDAQ:SODA): Upgrading To OW As Valuation Has Gone Flat - JPM

J.P. Morgan is upgrading SodaStream International (NASDAQ:SODA) to Overweight from Neutral with a $50 price target (prev. NA).

With the company reporting roughly in-line Q211 earnings and disappointing full year guidance, the stock has taken a major hit, dropping about 48% while the S&P has been up nearly 5% over that same time frame. While the stock has obviously lost momentum, they continue to believe that the short to medium term growth potential for SODA is strong and that their 2H guidance will prove to be too conservative. With the multiple having compressed from roughly 40x down to about 19x, 17x ex-cash, and with guidance that seems overly conservative, the firm thinks the stock is attractive here.

The details:

Growth is still there despite the conservative guidance. Even though SODA simply reiterated their FY11 guidance, which alarmed a number of investors, we continue to believe that SODA is a growth story. We believe the company’s 2H11 guidance is far too conservative as the company implied top line growth of nearly 31% for Q311, but only 10% growth YOY in Q4. Even though SODA faces a tough +59% comp in Q411, we note that their total US door count at this point (assuming no move into mass) has grown by +86%. In the end, we think that SODA's guidance will prove to be too conservative and we expect the test in mass (and a potential full roll-out) to provide upside to Q4 numbers. We are currently forecasting 16% revenue growth for Q4, but think our estimate could be too low.

At 19x our FY12 estimate, 17x after adjusting for cash, the stock is too cheap. With the stock down more than 50% from its high, we believe that stock is clearly much more attractive, especially as we believe there are no material changes to the story. With the rest of our group having re-rated positively since the market’s turn, SODA is just trading at a slight premium to the group.

US door growth is high, and trends continue to be strong at BBBY. We expect US doors to be up almost 100% yoy in Q4, and while the comps get more difficult, we still expect strong growth. Over the past few weeks we have contacted a number of Bed, Bath, and Beyond locations (BBBY locations are about 13% of US doors) to get an update on SodaStream products. Overall, it appears that machine and flavor sales, along with C02 refills continue to be strong, which is very encouraging.

We rate SODA OW. While the LT growth profile is less than the bulls would like to think, the ST results should be better than expected. Establishing a $50 price target for December 2012 based on 21x our 2013 estimate. As management discusses the conservatism baked into their Q4 guidance, we expect the multiple to move up

Notablecalls: SODA was a $80 stock back in the beginning of August. The recent high-flyer got smashed after management failed to raise guidance on its most recent conference call.

So now it's at $35 trading 19x EPS while growing EPS by 30%+. We saw a couple of tier-2 firms pound the table to bits on the way down, with little success.

Now we have a tier-1 firm out saying SODA is not a broken story and that things are going pretty well for them. JPM actually highlights some checks they made and these came back positive.

That carries some more weight. A lot more weight actually. Short interest stands at over 70%. The valuation is bound to adjust at some point.

One to watch. If this one gets going, the shorts will have one hell of a task keeping it down here.

Tape's drek but the lower we open the better chances we have for an outsized bounce in my humble opinion.

Friday, September 02, 2011

OmniVision (NASDAQ:OVTI): Post F1Q earnings sell-off overdone - JPM

J.P. Morgan's Paul Coster had a chance to touch base with OmniVision's (NASDAQ:OVTI) CFO, following his return from Asia Pacific region.

- The feedback?

Surprisingly positive.

Coster says he is now convinced that weaker-than-expected F2Q guidance originated in industry-wide weakness in the CE supply chain and does not originate in a head-to-head competitive loss at a Tier 1 OEM. For this reason, he thinks the post F1Q earnings sell-off overdone & recommends buying the OW-rated name.

The details:

Re-visiting F2Q Guidance. The CFO’s commentary is consistent with the earnings call. The weaker-than-expected (by sell-side analysts) F2Q guidance originates in several concerns: 1) slowing PC/Notebook sales, 2) component channel inventory build-up, 3) temporarily weak demand from some OEMs that are experiencing “transitions” (possibly RIM, Nokia), and 4) the later than expected ramp in BSI-2 product.

Head to head with Sony. OVTI’s CFO appeared unsurprised by Sony's August 30th CIS presentation and acknowledges that Sony is a credible competitor at 8MPx. That said, he believes OVTI has only gone head-tohead with Sony once (so far) and claims that OVTI won the resulting design opportunity for a 2012 product.

What about Apple iPhone 5? Consistent with past practice, the CFO will not acknowledge Apple as a customer, whether direct or indirect. That said, the CFO made the point that build lead-time for handset OEMs has collapsed to 30 days (from chip shipment to finished product in retail), and can be crammed down to 15 days under duress. We think this lead-time is surprisingly short, and is consistent with OVTI being well-positioned for the holiday ramp with Tier 1 OEMs (including Apple), notwithstanding the disappointing F2Q guidance. It is, for
instance, consistent with the notion that OVTI introduces BSI-2 8MPx product in late F2Q, and still captures Apple iPhone 5 opportunity if that product ships in mid/late October

What is the problem with BSI-2? The CFO denies that there are design issues with the BSI-2 chip, but acknowledges that the manufacturing process has not yet met the company's expectations regarding consistency. We view this as an engineering challenge that can be resolved in the next month or so.

Notablecalls: OVTI got clobbered a week ago following #'s. The reasons? There were 3:

- The conference call was just awful. I hope OVTI's management is reading this post. Guys, stop beating around the bush and get to the point. I had to read the transcript 3x and I still had hard time understanding what the heck was said.

- Concerns around Apple. It appears this call by Coster does a fairly good job putting some of these in bed. OVTI's CFO is hinting they still have the AAPL deal (we know AAPL & Sony went head-to-head on this).

- BSI-2. That's an issue. I'm not entirely sure TSCM can get this right in the next month or so. (Kudos to FBR on this! Brilliant call!)


All in all, I suspect OVTI may produce a bounce here following the JPM comments. Back above $18?

Tough call to make in this tape, obviously. Why not just buy the effin' market.

PS: I'm posting this after open.

Monday, August 22, 2011

Yingli Green Energy (NYSE:YGE): Tide turning? Avian & Piper upgrading

Yingli Green Energy (NYSE:YGE) is getting two upgrades from relatively smart operators this morning:

- Piper Jaffray is upgrading YGE to Overweight from Neutral with a $8 price target (prev. $11) noting the company solidly cemented its status as a tier 1 solar PV module supplier, as it continued to gain share through a difficult 1H11 by leveraging its low cost vertically integrated model and very strong brand recognition. YGE saw its shipments rise 36% q/q, while some tier 2/3 module suppliers struggled to maintain flattish shipments. Management expects shipment growth to continue in 2H11 as demand continues to improve, with expected price declines offset by declining costs, enabling YGE to maintain gross margins in the mid-high teens. Additionally,
YGE's PANDA module remains one of the highest efficiency modules shipping out of China today (20% of 2Q shipment, 80mw). Piper believes the significant pullback in the stock presents an excellent opportunity for investors to own one of the leading vertically integrated low cost module suppliers.

- Avian Securities is upgrading YGE to Positive from Negative with a $7.50 price target, representing 43% upside from current levels.

The seasonal trade in solar stocks will likely be compressed to just a few short months given the earlier demand delay caused by the subsidy uncertainty in Italy, but Avian finds YGE as a current outlier to the group that is likely seeing the early signs of the seasonal momentum coupled with increased market penetration. Following a decent Q2 report with both upside to revenue and EPS, the forward outlook was reaffirmed and is good enough to ease our near-term demand concerns. Avian notes waiting to upgrade after the PVSEC show in early September would put them in with the rest of the herd, but they hear the early signs from management’s comments that demand is increasing now for the seasonally strong solar installation period. The firm finds now is an opportune time to ride the wave of the solar trade, and to take the first dip with shares of YGE.

Notablecalls: Couple of points here:

- Piper's Zaman cut YGE back in March helping his clients avoid some of the slaughter in the name.

- Avian only recently picked up coverage in the space but their guys are well respected. I'm told by Avian they are definitely transitioning from a very negative opinion on the entire sector, to some positive opinions ahead of the seasonally stronger 2H.

That makes the YGE call potentially more significant. The co seems to be best-of-breed here (lowest cost producer etc.) and that's exactly the type of stuff you may want to be buying.

YGE has been crushed, so I expect a potentially explosive move off lows. The $6 per share level seems like the first logical stop in the n-t.

Friday, August 19, 2011

Research in Motion (NASDAQ:RIMM): Misek calling bottom

Jeffco's Peter Misek is upgrading Research in Motion (NASDAQ:RIMM) to Hold from Underperform while raising his target to $25 (prv. $22).

- I would probably have ignored the Hold rating from Misek but going over Marvell Tech's (MRVL) conference call transcript I noticed two interesting tidbits:

* MRVL was calling for RIM revenue to stabilize in H2

* Sehat Sutardja Marvell CEO had the following comments on the conf call:

I think investors should not discount RiM. We continue to work closely with RiM in delivering new solutions. They will make the product to look really, really nice, better performance as well. So, don't discount that. Don't discount RiM at all.


Here are the details:

We believe the share price has finally found a floor after months of misexecution, delayed products, and shrinking market share. Our reasons for the more positive view are: 1) patent values based on recent transactions point to higher sum of the parts; 2) build plans have stabilized; 3) focused on releasing QNX before expectations; 4) removal of WebOS. We are upgrading RIM to a Hold from Underperform and raise our price target to $25.

New value for patents: Based on the recent MMI acquisition by GOOG, Nortel acquisition by the consortium, and stock price activity of IDCC, it is clear there is significant interest in the market for patents. By our calculation RIM spent over $5B in acquiring and developing its patent portfolio but we RIM could monetize its patent portfolio for approximately $2B since many of the patents are uniquely security-related or cross-licensed.

Build plan stabilization: our checks indicate that builds plans have begun to stabilize.

Rush to release QNX: we believe that RIM will likely dump features to release new QNX based devices before expectations. While it may not be the superphone we hoped for, we believe it is slightly positive as it demonstrates to investors the ability to execute on time. Chance to become third ecosystem increased: The removal of HP WebOS as a competitor increase the low probability that RIM as an ecosystem vendor may recover.

Salvage value revisited: our scenario analysis assumes a breakeven hardware business, a subscription business run as a cash cow, a monetized patent portfolio, and a $700M restructuring charge. The share price calculation then is $3B net cash + $2B (patents) - $700M restructuring charge + subscription NPV all divided by 524M shares outstanding. Our new $25 target implies a 2.5% annual rate decline and 3% annual subscriber decline.

Blackberry Music Service: RIM is seeking to leverage the popularity of BBM by integrating a music service. According to CNet the company has already signed a deal with at least one of the "Big 4" record labels. We believe this is awfully late relative to competitors, but given the popularity of BBM, it may help the company gain more traction with the consumer market.

Valuation/Risks
Our $25 target is ~8x our FY13 ests (2-year range 7x-18x). Risks: 1) transition to new OS is poorly executed; 2) share loss in both consumer and enterprise.

Notablecalls: Misek turned negative on RIM at the end of April when the stock was still trading in the high $40s, slashing his price target way below the Street average. If my memory serves me correct his $22 price target was the Street low. Until this morning that is.

Bernstein's Ferragu & Misek were the two notable bears in RIM. Now both have told their clients to cover.

I think this coupled with the MRVL CEO comments, upcoming QNX launch and low expectations could produce a bounce in the name in the n-t. Barring a general market crash of course.

Needless to say, executing the trade will be difficult.

Tuesday, August 16, 2011

Notable Calls Network (NCN): Wedge Partners on BIDU

Notable Calls Network (NCN) caught a very nice call in Baidu.com (NASDAQ:BIDU) yesterday. We were super-early on it, which is just the way we like it.

- Around 10:30 AM ET a contributing member of NCN told me to get short BIDU fast as Wedge Partners, independent equity analysis firm with a focus on the technology and media industries was making a big negative call in the name.

A minute later I received the details:

VERY NEG BIDU (Confirmed just now by analyst in Beijing).... Just now (literally 10 mins ago) on CCTV2 a popular TV show, Baidu was exposed by CCTV about providing unreliable advertisement to consumers, accepting ad for healthcare companies without business license and etc.

Remember, at the end of 2008, Baidu's stock price more than halved by the 2-days continuous attack from CCTV. Baidu's stock might be materially impacted by this short term.

Knowing how potentially significant this call could be, I swiftly distributed the details to other Notable Calls Network (NCN) members. This was exactly the type of info people were looking for.

- Over the next 30 minutes the stock started breaking down as more details emerged:

1) BIDU provided links to fraudulent websites for consumer goods and travel agency services. Consumers who followed the BIDU search results to these sits and made online payments were victims of fraud as the online travel agencies and consumer goods companies were not real.

2) The show highlighted how BIDU’s own sales force (Wedge's Lin Juan actually believed they are probably BIDU’s distributor sales folks) actually advised and helped companies who did not have qualifying licenses help fake or bypass the issue.

3) The show also mentioned and brought up the entire 2008 scandal related to healthcare companies who did not have proper licensing.

Link: CCTV exposure caused by Baidu search site users provide false deceived


- By 11:30 AM ET the stock was down 7 pts. A hefty intraday trading gain.


PS: Morgan Stanley is out this morning with a cautious call on BIDU saying they expect some pressure on the stock price, as CCTV's claims appear more widespread this time (vs. 2008), covering more than only healthcare listings.

The firm has issued a Negative Research Tactical Idea saying the share price will fall relative to the country index over the next 30 days. They estimate that there is about a 70% to 80% or "very likely" probability for the scenario.

The stock is trading around $140 in pre market, another 4 pts lower from yesterday's close.

Obviously, Wedge Partners deserves a Kudos here. They beat the rest of the Street by a mile.


This is how Notable Calls Network (NCN) works - sharing the flow. We catch them every day.


Want to be part of NCN?

It's easy. Just shoot me a brief email that includes a short description of yourself and your AOL nickname.

Please do note that contacts via IM are limited to people with:

- 3+ years of trading experience

- Access to quality research/analyst commentary

- Ability to generate and share (intraday) trading calls

I will not accept contacts from purely technically oriented traders, penny stock fans or people who have less than 3 years of experience in the field.

Wednesday, August 10, 2011

MetroPCS (NYSE:PCS): Bargain hunting - Upgraded to Outperform at Bernstein

Bernstein's Craig Moffett is telling his clients to go bargain hunting in the Pre-Paid Wireless space this morning.

- Moffett is upgrading MetroPCS (NYSE:PCS) to Outperform from Market Perform with a $16 price target.

He writes:

The sell-off in telecom stocks has been nothing short of breathtaking in recent weeks, with many stocks in the sector down 40% or more. The pre-paid wireless operators have been particularly hard hit. Since July 1, a month before it reported Q2 results, Metro's stock price has declined -47.5%. Leap Wireless is down a mind-bending -58.9%. The S&P 500 has fallen -12.5% during the same timeframe.

Sector concerns are not unwarranted (we ourselves have been among the most bearish). But of all the stocks that have sold off in the telecom sector, MetroPCS looks to us to be uniquely oversold, and we believe it presents the best buying opportunity. In this report we take a fresh look at the pre-paid players. We’ve scrubbed our models from top to bottom, refreshed our valuations, and closely examined the segment’s recent performance.


- The pre-paid segment appears less profitable than it once had, as the margins associated with smartphones are lower than the voice-only margins of old. But the pre-paid operators continue to gain share, and the prepaid market does not look like it is fundamentally broken. Pre-paid and reseller captured 60% of industry net additions in Q2, 390 bps better than Q2 last year, and MetroPCS remains by far the industry's standout performer on a footprint-adjusted basis.

- By Bernstein's estimates, Metro's forward EBITDA multiple (just 3.9x 2012 EBITDA) is the lowest it has ever been on an absolute basis, and surprisingly, it is lower than Leap’s.

- In contrast, Leap Wireless’s outlook is far more uncertain, and its valuation far less flattering. Given its enormous effective leverage, optimistic scenarios could yield spectacular upside. But firm's valuations suggest that even in their base case scenario, there could still be additional downside to the name, and more pessimistic assumptions yield outcomes with no equity value at all.

Of all the stocks that have sold off in the sector, MetroPCS looks to be uniquely oversold, and Bernstein believes it presents the best buying opportunity for intrepid investors.

By most measures, MetroPCS posted Q2 results that only modestly missed investor expectations; certainly, its business shows no sign of existential distress. Indeed, it appears well positioned to benefit from a continued trade-down from high priced post-paid wireless plans into its discounted pre-paid plans. PCS's numbers were unquestionably far better than that of unlimited pre-paid peer Leap Wireless’s. To be sure, both MetroPCS and Leap missed consensus net additions, but Metro by a far smaller margin. And irrespective of the miss, Metro’s net additions were still a healthy positive number; Leap’s were - 103K (voice net adds of 29K and broadband net losses of -132K, compared to expectations of 89K and - 34K, respectively). And gross additions at MetroPCS actually beat expectations, in a clear sign of sustained strong demand (Leap's gross addition results, by contrast, fell short). ARPU was also close to expectations, missing by a narrow $0.17, while Leap actually outperformed, beating expectations by $0.46.


All in all, these results felt like ones that would normally have dinged MetroPCS’s stock price by several percentage points, but probably not much more. (Leap’s results were worse, and given their volatile trading history one might reasonably have expected a bigger drop).

As anyone who follows the space is surely aware, things did not exactly pan out that way.

.....

To be continued. This is a 32 pg. note so I can only pass on the broad stroaks.

Notablecalls: So Moffett is telling people to buy PCS, which has according to him has gotten unjustly punished.

Given he has been among the most cautious on the Pre-Paid space his change of heart will likely generate enough attention to get PCS moving up.

I'm guessing upwards to $10 in the n-t.

This may prove to be a significant call.

Tuesday, August 09, 2011

The Market - Bounce?

Pick your favourite high-beta names because it seems we're going to have a big bounce today

Notablecalls: Water pistol to head call!

Thursday, August 04, 2011

Just a heads up - An indicator we follow technically just shot off a positive reading suggesting a bounce - Avian

I know we generally don’t put out technical analysis but I thought this was interesting enough to highlight.

Avian’s 10 Week Hi-10 Week Lo indicator fired off its extremely oversold reading of -556. As you can see on the below chart, whenever the red line spikes higher, especially above 400, the market is at a tradable low. The indicator does not shed any light on whether this bottom is a major or minor one. But it should provide a tradable bounce.

Notablecalls: Sometimes we have to rely of stuff like this.

Intermune (NASDAQ:ITMN): Next to blow up?

Jefferies is out with a rather well-timed call on Intermune (NASDAQ:ITMN) saying it could be the next Dendreon (NASAQ:DNDN) to blow up.

Ahead of Esbriet launch starting this September in Germany, they view ITMN shares as likely to come under further pressure given likely slow uptake (vs. consensus high expectations) and potential financing risk (cash enough thru 2012). On very modest sales of Shionogi's Pirespa in Japan and competitors in the works, high expectations for Esbriet may need to be adjusted near term.

- Firm is lowering their target to a Street low of $18 (from $24) & is reiterating Underperform rating.

New drug sales are increasingly dictated by drug efficacy/cost-benefits, not necessarily by a lack of other approved drugs or by the large # of eligible patients, particularly in the current HC cost-sensitive environment. Bull case for ITMN is that there is no alternative for IPF patients; so once launched, Esbriet would be rapidly/widely used, and eligible IPF patients would continue to be on the drug once started. However, given the very modest efficacy of Esbriet, the firm views uptake would be slower and adherence is debatable due to side effects (nausea ~20%, rash ~20%, dyspepsia ~11%, photosensitivity reaction ~11%, placebo-adjusted). While ITMN estimates Esbriet-eligible IPF patients in EU at ~70K, the real question is how many will actually receive Esbriet and continue to stay on the drug. Based on the disappointing launches of several biotech drugs, in jeffco's view it is hard to be convinced why the Esbriet launch would be drastically different.

Lowering their already below-cons Esbriet sales estimates by ~33% & their PT to $18; consensus #s need to come down significantly, in our view. Jefferies notes they now assume ~$400M/$400M in peak EU/U.S. annual sales for Esbriet (vs. ~$670M/$530M previously. For 2011/2012, consensus of $10M/$105M (vs. Jeffco's of $2M/$35M) implies ~880/~2,330 patients being treated with Esbriet (vs. their ~176/780 pts) at assumed $45K/pt/yr.

Estimated current cash balance of ~$200M may not be sufficient through 2012 by our estimates, thus posing financing risks. ITMN currently has ~$85M in convertible debt due in 2015 (coupon rate/conversion price of 5%/$18.88), with a long-term debt-to-capitalization ratio of ~33%.

Notablecalls: With Dendreon (DNDN) crushed last night on lower-than-expected Provenge ramp the timing of this call couldn't have been better (or worse, depending on one's point of view).

JPM's Biotech analyst Cory Kasimov notes this morning: 'As if investors needed another reason to “short the launch” of one-product biotech companies, DNDN just served up the ultimate case study.'

Kasimov's right, investors have seen too many one-trick ponies get slaughtered after analyst estimates collide with reality. Esbriet with its $45K price tag & low efficiency fits right in.

Now Jeffco is saying ITMN may end up being another disappointment. This means stock will likely be taken to the back of the woodshed today and shot.

ITMN could be down as much as 7-10% today, putting 28-29 levels in play.

This could serve as a meaningful overhang for quite some time, so the stock could move lower than that.


PS: I'm posting this at around market open 9:30 AM ET

Tuesday, August 02, 2011

AGP, CNC - Texas Medicaid Awards Largest in History

Texas announced the awards for its highly anticipated $10 billion Medicaid managed care program. The public MCOs dominated the RFP and captured most of the new contract awards.

This was the largest, and therefore the most highly anticipated Medicaid RFP in the history of the Medicaid program. Analysts believe the overall size of the Texas market after full implementation of this expansion will be roughly $12 billion, more than doubling its previous total. The operational start date is March 1, 2012, which suggests that the full earnings potential from these contracts will not be felt until 2013.

There are two major winners:

1) Amerigroup (NYSE:AGP) - AGP will remain the largest Medicaid plan in Texas and should generate around $1 billion in incremental revenue from the Texas expansion. Upon completion of the expansion, AGP should generate over $2.5 billion in annual revenues in Texas Medicaid.

2) Centene (NYSE:CNC) - Centene will generate around $1.5 billion of incremental new revenue in Texas expansion, thus continuing its hot streak as the company also recently won new contracts in both the Louisiana and Kentucky RFPs.

Here are some estimates of EPS impact across Tier-1 firms:

- Deutsche sees $0.40-0.60 2013 EPS impact for AGP, $0.55-0.83 for CNC.

- J.P. Morgan sees eventual run-rate EPS impact for both CNC and AGP to be about $0.50 per share additive

- Credit Suisse notes assuming a pretax margin of 3%, they estimate the following annualized aftertax EPS impact: AGP +36c, CNC +22c

- Barclays estimates that CNC will generate an incremental $0.25 in EPS in 2012, and an additional $0.54 in total run-rate EPS once the new members are fully phased in. They estimate that AMERIGROUP will generate an incremental $0.22 in EPS in 2012, and an additional $0.40 in total run-rate EPS once the new members are fully phased in.

Notablecalls: Considering AGP, CNC trade 10-11x EPS and the EPS impact is around $0.50 for both companies in 2013, both stocks should be up 3-4 pts (im sure some of the impact was already priced in).

Could be some more for AGP as the stock got crushed following earnings last week. I see Citigroup is raising their target on AGP to $76 (from $71) this morning.

Difficult to call any trades here but it's where the action will be this morning, I suspect.

Wednesday, July 27, 2011

Investment Technology Group (NYSE:ITG): Deep Value! Upgrade to OW - JPM

J.P. Morgan is upgrading Investment Technology Group (NYSE:ITG) to Overweight from Neutral with a $16.50 price target calling it a deep value stock.

- Upgrading ITG to Overweight – Unloved and Largely Ignored, But Management and the Board Have Options.

- With some help from ITG's balance sheet this could be a $18 stock, according to JPM.

With the stock underperforming materially in 2011, particularly since preannouncing soft 2Q11 results on July 12,
2011, the firm see management having capital management options that could be particularly positive for investors. The core of JPM's thesis is two fold –

1) ITG has the free cash flow to borrow against a cash rich balance sheet and buy a materially percentage of its stock.

2) An expense reduction program gives ITG meaningful flexibility should equity volumes remain subdued, but meaningful earnings potential should volumes rise.

JPM believes that ITG’s mgmt. is well positioned to be more aggressive in returning capital to shareholders, taking advantage of the recent steep drop in its stock. Over half of ITG’s ~$12 stock price is in cash – they estimate ~$7 per share. While much of this cash is trapped to support the business, ITG’s mgmt. has only been returning moderate capital to shareholders. However, with share price down 27.5% in 2011 and Private Equity in the sector, they think that pressure is on mgmt. to create additional shareholder value. Borrowing $170mn (1.5X trough 2Q11 EBITDA) and using the proceeds to purchase shares at $13 would increase ITG’s 2012 EPS by 30%, driving the stock to $18, at 12X earnings.

Management has listened to shareholders in the past, initiating a stock repurchase program following encouragement of D.E. Shaw in 2007. Given a significant decline in ITG’s stock price, they see the potential for the CEO and Board of Directors to take stronger action to deliver shareholder value.

ITG fundamentals challenged in 2Q11, but earnings outlook acceptable given cost cutting initiatives. ITG’s earnings are tied to equity trading commissions, which were solid in 1Q11, but struggled in 2Q11. However, mgmt. announced a meaningful expense reduction program in early July to offset recent softness in industry trading volumes. This program should not only mitigate weak volumes should they persist into 2H11, but increases ITG’s leverage to better trading volumes in a seasonally stronger 1Q12.

According to JPM, ITG’s market share of total NYSE and Nasdaq shares traded has increased from 2.75% in the beginning of 2010 to 3.3% at the end of June 2011.

ITG – A Deep Value Stock
Firm thinks ITG is especially inexpensive. After peaking earlier this year at ~$20 per share, the stock has declined as both industry volumes sank and as the perception of ITG’s customer mix deteriorated from higher fee paying mutual fund customers to lower fee paying brokers and lower touch customers. ITG stock has fallen 27.5% in 2011, including a 21% decline earlier in July following its earnings preannouncement.

ITG Trades at 10x JPM's 2012 Estimate of $1.18, FCF Yield Is An Attractive 13%. ITG trades at 15X what they expect will be trough earnings in 2011, and an inexpensive 10X times their 2012 estimate. Similarly positioned company, such as Knight Capital is trading at 8X JPM's 2012 estimate. However, ITG has a much higher FCF yield relative to Knight Capital – ITG's 13% based on 2Q estimates vs. Knight's 8%.

ITG Has No Sell-Side Support – No One on the Sell side Has a Buy on ITG! JPM believes there are a number of data points to suggest ITG is being ignored by the investment community. One example is that of the nine analysts that provide research coverage on ITG, there are no ‘Buy’ ratings – eight analysts have “Holds’ and one has a ‘Sell’. Firm notes that according to Bloomberg, 7% of the float is held short.

Notablecalls: What do you think will happen to a $500M company (a small-cap!), that nobody loves & seems to have forgotten about when a Tier-1 firm like J.P. Morgan comes out swinging calling it a Deep Value play with a hefty 50%+ upside price target.

It goes up! Big time.

I'm guessing +7-10%, putting 12.50-13.00 levels in play in the n-t.


PS: I'm posting this at Market Open 9:30 AM ET.