Monday, July 25, 2011

Bridgepoint Education (NYSE:BPI): Warburg files S-3 - 35 million shares

Bridgepoint Education (NYSE:BPI) may offer an interesting trade in the n-t after Warburg Pincus, majority owner & founder filed to sell their 35 million stake in the company.

Here's the S-3 filing

Here are some points why this may be a major event for the company:

- Bridgepoint Education Inc. (BPI) was formed in 2004 by current CEO Andrew Clark and Warburg Pincus to establish a for-profit post secondary education provider. The IPO was priced at $10.

Warburg & co can be considered 'smart money' & seeing them cash in their chips should be considered as a red flag.

- Warburg owns 34.6 million shares or about 57% of the fully diluted shares outstanding.

While short interest stands at a whopping 72% of float, the float is about get significantly larger. Current float stands around 18M shares.


I think the recent raise in BPI stock price can be attributed to a short squeeze. As you can see from the Bloomberg chart, short interest has been declining lately, while the stock has been going up.

All in all, Warburg filing is likely to have created a significant overhang for the stock in the near-term.

Thursday, July 21, 2011

Notable Calls Network (NCN): InterDigital (NASDAQ:IDCC)

We caught a nice mover on Notable Calls Network (NCN) this morning:

InterDigital (NASDAQ:IDCC) has been on fire ever since the Nortel wireless patent estate was auctioned for $4.5 billion. InterDigital happens to hold patents related to the fundamental technologies that enable wireless communications.

The stock has gone from $35 in mid-July to a high of $82.50 as of this morning on speculation Google, Apple among others may be interested in buying the company for its patents.

All in all, it's been the main hype name that traders love to trade around on any new bits if info.

- This morning, around 8:00 AM ET a senior member of NCN brought to my attention that Peter Misek, an analyst at Jefferies & Co had an interesting call on IDCC saying Apple could potentially buy the company. What was even more interesting was the fact he thought IDCC patent estate would be worth up to $10 billion for Apple. IDCC's market capitalization was around $3.1 billion.

This was clearly market moving material, so I quickly distributed a short summary of the call to our wonderful members:

IDCC (Peter Misek) - InterDigital portfolio could be worth up to $10B to Apple = $200 per share!

InterDigital's patents could save Apple $3-$10 per handset and could substantially increase the price of the low-cost Android phones launching in H2:11.


- Sellers were scarce, so one had to buy up 4-5% to get decent fills. But as you can see from the chart it was well worth it. The stock went up another 10 pts.

You can probably imagine the profits some people have from this morning.


This is how Notable Calls Network (NCN) works - sharing the flow. We catch them every day.

Want to be part of NCN?

It's easy. Just shoot me a brief email that includes a short description of yourself and your AOL nickname.

Please do note that contacts via IM are limited to people with:

- 3+ years of trading experience

- Access to quality research/analyst commentary

- Ability to generate and share (intraday) trading calls

I will not accept contacts from purely technically oriented traders, penny stock fans or people who have less than 3 years of experience in the field.

Wednesday, July 13, 2011

OpenTable (NASDAQ:OPEN): Reduce Estimates on Slowed Subscriptions and Soft Spotlight - Benchmark

Benchmark is out surprisingly cautious on OpenTable (NASDAQ:OPEN) lowering their Q2 revenue estimates on increased competition and weakness at Spotlight, OpenTable’s deals product.

- Firm maintains Hold rating and $90 price target.

The details:

OpenTable appears to be facing more competition domestically from Urbanspoon’s RezBook, Livebookings and Eveve. CityPages recently reported that two notable restaurants in the Twin Cities dropped OpenTable. These restaurants apparently switched to Eveve, a European competitor that has 300 restaurants, due to lower cost and more flexibility. Competition may be slowing OpenTable’s restaurant growth. Our checks indicate OpenTable added meaningfully fewer restaurants in 2Q compared with prior quarters. We reduce our 2Q estimate for restaurant subscription revenue from $12.8 million to $12.4 million. This could affect reservations as well.

We believe at Spotlight, OpenTable’s deals product, revenue was down sequentially in 2Q11. For 2Q11, we now estimate Spotlight’s revenue at about $800,000, below our prior $1.5 million estimate, and down from $1.2 million in 1Q11. While there was an improvement in Spotlight revenue from April to June, no single month in 2Q11 was higher than March’s total. Large markets such as San Francisco (down an estimated 46% sequentially), Los Angeles (down 43%) and New York (down 34%) drove the projected soft result.

The National Restaurant Association reported weakening restaurant trends for May, the latest available data. The Restaurant Performance Index dropped 1% sequentially, from modest expansion to modest contraction. This was the first time in six months that the Index signaled contraction. Expectations for the next six months also declined slightly.

Consensus 2Q11 revenue, EBITDA and EPS are $35.5 million (45% y/y organic growth, $13.0 and $0.27 (91% y/y growth). Our revenue estimate drops from $36.3 million to $35.0 million. Our adjusted EPS drops from $0.32 to $0.29.

European competition remains a concern. Livebookings appears to have 8,700 restaurants in 23 countries, and seats one million diners monthly, mainly through its website bookatable.com. Livebookings main markets are the UK and Germany where it has about 5,000 and 2,000 restaurants, respectively. These are also OpenTable’s main European markets.

OpenTable closed at 62x and 32x 2011E adjusted EPS and EBITDA with about 50% average annual growth in both.

Notablecalls: Benchmark's Clayton Moran is making a potentially significant call here. If his checks are right, OPEN's huge valuation multiples are about to compress.

The weakness at Spotlight doesn't sound good either but seems to be well telegraphed by now. Still a big part of OPEN's valuation, though (based on Groupon-like multiple)

Imagine OPEN reporting slightly below consensus #'s on August 2. Ugh.

Note that 3 weeks ago PAA Research, a small shop with interesting ideas & a good track record published a very negative take on OPEN. They called it a short with a $55 price tag noting competition was quickly eating away OPEN's total addressable market. The stock is up 5 pts since.

Very volatile name so adjust your risk accordingly.

PS: I'm posting this around 9:30 AM ET
.

Monday, July 11, 2011

Lam Research (NASDAQ:LRCX): Samsung's Gift to Semicon; Upgrade to Buy - Citi

Citigroup's Semiconductor Equipment team is making a significant call on the space, turning bullish again after several months of being very bearish. Title of the call is "Samsung's Gift to Semicon".

- Lam Research (NASDAQ:LRCX) is their new favourite pick in the space, after being on Citi Top Pick Live Sell list since April 6. They are upgrading LRCX to a Buy with $62 price target (prev. $43).

ASML and KLAC get upgraded to Hold from Sell. NVLS & AMAT remain at Hold.

Not only has LRCX meaningfully underpeformed the group in 2011 and back to historically attractive valuation levels, but should also be a significant near-term beneficiary from Samsung, according to Citi.

The details:

Samsung is finally coming back; increasing CQ3 from -10-15% to flattish — Citi's most recent checks indicate that Samsung is finally coming back to the table to place many of the orders pushed out in April. Specifically, the firm now thinks Samsung will take 20k wsm capacity for Line 16 phase 2 NAND ramp and ~30k wsm tool upgrades for Line 15 DRAM shrink, both of which should now order and ship in CQ3. They estimate this is nearly $1B of the ~$1.5B previously pushed out – a swing factor of ~15% on a wafer fab equipment order run rate of ~$6.5-7B for CQ2.

Overall, we believe this amounts to nearly ~$1B that should come back into CQ3, which should provide ~10-15% of the upside for CQ3 orders/shipments for the major front-end names. This essentially “fills the gap” between what the firm thought was previously a down 10-15% CQ3 and now looks more flat.

Importantly, Citi believes this should start to come through this week at the Semicon/WEST tradeshow and be reflected in surprisingly good sentiment for CQ3 relative to current Street expectations.

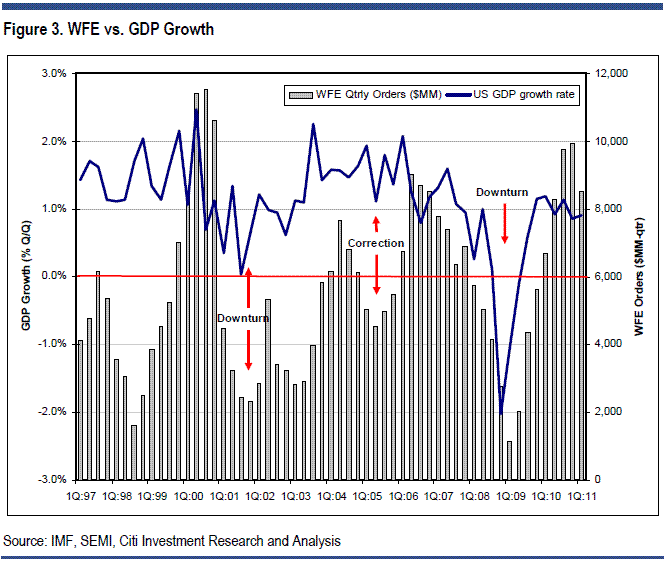
- Orders now below normalized levels, baking in $27B WFE — Citi estimates CQ2 wafer fab equipment (WFE) orders were back to ~$27B/yr run-rate, down from >$40B in CQ4:10 (fueled largely by ASML) and below the ~$29B/yr they consider “normalized”. Not only is this decline consistent with the correction magnitude in ‘04/’05 (the last supply-driven correction, ’01 and ’08 were demand-driven where GDP slowed meaningfully), but $27B WFE would be down ~15% from the $32-33B still suggested by equipment companies and bottom-up capex analysis for 2011.

Citi's sector view — While supply has ramped in face of end-market demand questions + IC inventory headwinds, the sudden and meaningful order pullback has mitigated risk while Street sentiment now very negative. Looking to 2012, it is hard to see a big down year given rising capital intensity, lack of memory over-spend, and INTC “changing the game” in the foundry segment. Their tgt increases are based on a new higher normalized mkt size due to higher capital intensity. LRCX/TER/FORM remain top ideas.

Notablecalls: Citi's Timothy Arcuri caused 8% intraday drop in LRCX on April 6, when he issued a Top Picks Live Sell rating on the name, claiming Samsung decided to push out shipments with the company.


April 20 results & guidance by LRCX confirmed his suspicions sending the stock further down.

Goldman Semicap analyst upgraded LRCX on May 5 but the selling pressure was so intense the stock failed to hold gains even for the day.

- Now we have Arcuri coming out saying his uber-negative thesis is now reversed. Following recent underperformance & Samsung resuming orders LRCX is his favourite name in the group.

If that's not a big call I don't know what is.

Plus we have Semicon/WEST the biggest Semi event starting tomorrow July 12. Citi thinks this could ignite the group.

All in all, I suspect LRCX will trade up markedly in the n-t. It will almost certainly produce a 3-5% upside move from open but given the significance of the call this could push the stock up for several days. So buying the pull-back could work here as well.

Buying the other names in the sector may prove to be somewhat more tricky as we have UBS & Merrill both out with cautious pre-Semicon comments lowering their cap-ex growth rates for the space. They are obviously lagging behind Citi checks wise.

Tape's drek so adjust your risk accordingly. It seems we're in a state of panic this morning. Quite the change from Friday's jolly bounce.

PS: I'm posting this at around 09:30 AM ET.

Friday, July 08, 2011

Google (NASDAQ:GOOG): Investment Ramp, Uncertain ROI, Downgrade to EW - Morgan Stanley

Morgan Stanley is downgrading Google (NASDAQ:GOOG) to Equal-Weight from Overweight with a $600 price target (prev. $645).

- Google is spending to innovate in social / local, retain talent, and to drive user adoption of key products, but those investments have uncertain ROI / payback periods. Morgan Stanley is reducing their PT to $600 (from $645) and C2012e EPS to $34, below consensus of $40.

Details:

Debate #1: Will margins decline from here? Yes. Given Google’s aggressive hiring plans, rising compensation expense, and significant advertising spend on Chrome & other Google products, we expect EBITDA margin to decline in C2011 / C2012.

Google is now hiring at a blazing pace (1,900+ net hires in CQ1) and is likely to attain its goal of making 2011 its “biggest hiring year in company history” – per Alan Eustace, Google’s SVP of Engineering & Research“. As a result, we believe the company is on track to hire 7,000 employees this year (an increase of 19% from year-end C2010), up from our prior estimate of 4,000 net additions.

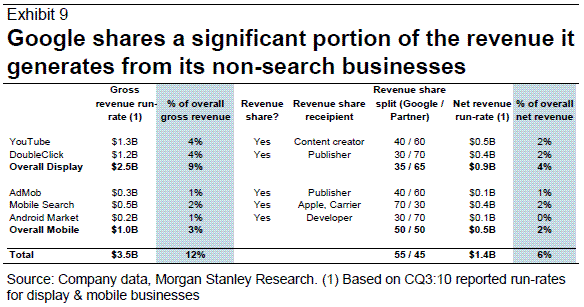
Debate #2: Will “newer” businesses drive near-term revenue outperformance? No. We believe the consensus is too optimistic on the net revenue contribution of newer businesses, such as DoubleClick, YouTube, AdMob, Android Market, and mobile search. In 2011, we expect search & contextual ads to contribute ~90% of Google’s net revenue.

Debate #3: Will investments in local eCommerce and / or social pay-off? Too early to tell. We are encouraged by early progress of Google Plus and Google Offers, but Google faces stiff competition from incumbents who have first mover advantage. The pay-offs of such endeavors may be longer-term.

Google’s approach to capturing markets is to grow users / market share first, and monetization (profitability) second. We expect them to take a similar approach with Google Offers and Google Plus, which should limit near-term financial contribution even if both products prove successful. Further, these businesses appear to be scale businesses whereby the highest margin profile accrues to the market share leader. If Google is not able to capture a leadership position in the market, it may not enjoy EBITDA margins as high as in its core business.

As a Result, We Are Reducing Our Estimates
We are reducing our profitability estimates (now significantly lower than consensus) due to the following: 1) Google’s aggressive hiring plans, 2) rising salaries due to a competitive hiring environment, and 3) increased advertising spend to drive usage of new / existing products.

Our new CQ2 / C2011E EBITDA estimates are $3.44B / $14.5B, roughly 4% / 5% below consensus estimates. Our revised CQ2 / C2011E operating EPS estimates are $7.45 / $31.44, approximately 5% / 7% below consensus.

Notablecalls: Morgan Stanley has been a Google Bull since 2008. So that makes the call potentially a significant one.

Thursday, July 07, 2011

LinkedIn (NASDAQ:LNKD): Initiating Coverage with a SELL and $45 price target - Capstone

Capstone Investments is making the call none of the other Wall Street firms want to make:

LinkedIn (NASDAQ:LNKD): Initiating Coverage with a 'SELL' and $45 price target - Price isn't the Only Risk

- The 18 pg note accuses the online recruiting firm of creative accounting, lower-than-advertised user base, high fixed cost business model and poor corporate governance.

All this they say, comes with a bubbly valuation not seen since 1990's. According to Capstone, their Street low $45 price target could prove to be too optimistic as the company fails to execute its ambitious business plan & insiders start dumping the shares. IPO lock-up expires in November 2011.

'... LinkedIn is an online professional identity and recruitment tool. Sprinkle on the "social media" moniker and in the Internet Bubble 2.0 you can price an IPO at $45per share, or 34% higher than the price talk midpoint, and the watch the stock rise to $94.54 - although it has been as high as $122.70 and as low as $60.14 over the sex weeks since LinkedIn's stock offering - to give this break-even business a $93.4 billion market cap. ... '

Paul Meeks, CFA at Capstone

The PDF file is copy-locked so I can only show you the Summary page of the note:


Notablecalls: There are two reasons why LNKD has only Buy ratings from major Wall Street firms:

- Merrill, JPM, Morgan Stanley & UBS were the underwriters. They need to keep their clients (both sides) happy.

- Facebook. The biggest IPO in recent memory is expected some time in 2012. Everyone wants a piece of the action and they are not going to get it by issuing Neutrals (or god forbid Sells) on other Social Media names.

That leaves the door open for Capstone to come in with a seriously scary story and a price target that should send people selling at least in the n-t.

I expect LNDK to trade down today, possibly to the tune of 5-10%, putting $89-85 levels in play.

Wednesday, July 06, 2011

Omnivision (NASDAQ:OVTI): Actionable Call Alert!

FBR Capital Market's Semiconductors team is out with a call on Omnivision (NASDAQ:OVTI) that I suspect could be a game-changer for the stock in the n-t.

- First I would note that FBR doesn't officially cover OVTI (yet!) but seems they stumbled upon the info while doing their Apple supply chain checks.

The firm discusses their iPhone/iPad estimates going up etc.. until it reads this buried in page 2:

We still expect the iPhone 4S (codenamed N94), to have an 8 mega-pixel camera though we hear reports that OmniVision may be having technical difficulties with its new CMOS sensor, possibly risking its iPhone socket supplier status. As reported previously, Apple’s iPhone 4S refresh has replaced Infinieon’s baseband processor with Qualcomm’s processor. Also of note, with 72.5M iPhones set for production through the first three quarters of 2011, 100M iPhone builds again seems reasonable for Apple this year. Given our new iPhone build estimates, for 2Q11 we now estimate Apple can sell a maximum of 21M units, and for 3Q11 we now estimate Apple can sell a maximum of 27M units (though actual sales will likely be lower as Apple builds more internal and channel iPhone inventory before holiday sales ramp in 4Q11.

Omnivision possibly out, Sony may pick up the slack. Our contacts tell us that Omnivision may have missed Apple’s commercial production deadline for products utilizing their BSI-2 architecture, and thus may have lost the lead supplier status for the image sensor socket to Sony. Omnivision’s BSI-2 technology is the world’s first 1.1-micron pixel architecture allowing for low-light sensitivity and accurate color reproduction for better overall image quality. Manufactured through Taiwan Semiconductor, it is built using a 300 mm copper process at the 65 nm node. However, we understand that yield rates at TSM have thus far been unacceptably low for commercial viability, and that the deadline for inclusion into the next iPhone has passed. Therefore, Sony could become Apple’s primary supplier of 8 mega-pixel CMOS image sensors for the next iPhone, with OmniVision possibly being a backup supplier. Many believed that Omivision would capture as much as 90% share of iPhone production, which may turn out to not be the case.

Notablecalls: FLASHBACK: February 23, 2011 - Sony could win all of initial iPhone 5 procurement orders - Baird

Baird's Tristan Gerra made a bold call just 2 days ahead of earnings saying Apple could potentially single source iPhone 5 sensors from Sony. This resulted in a 3 pt (15%) drop for the stock. OVTI was a 26 dollar stock back then.


The analyst was proven seemingly wrong as OVTI guided July qtr tad above guidance, implying all was good at Apple. The stock surged 10 pts as disgraced shorts fled the scene.

The consensus view became that OVTI's OmniBSI-2 technology would be in the iPhone 5 & Sony would at best be a me-too supplier.

That's until today.

FBR's ever-wonderful Semi team is saying OVTI is having real problems with the BSI-2 architecture as yields are way lower than expected. Low yields is the key to this call. You see, OVTI is converting its sensors to BSI technology because of better yields and lower defect densities.

I can't stress this enough but if OVTI cannot mass produce BSI-2 architecture, it means they can't get their stuff in the high end devices like the iPhones & iPads. That would mean consensus #'s are way too high.

Someone call the homicide unit because that would mean murder for the stock.

FBR could have it wrong with their checks. Maybe it was just a patch of BSI-2's that had bad yields & TSM being best in the business can turn it around for them. But with the stock 10 pts higher from where the concerns first surfaced, one can expect a rather painful reaction.

I would not be surprised to see the stock down 10% or more today after the FBR call makes the rounds.

That would be $31.50 or lower in the n-t.

Actionable Call Alert!

Netflix (NASDAQ:NFLX): Downgrade to Neutral - Merriman

Netflix (NASDAQ:NFLX) Merriman downgrading to Neutral on near-term margin pressures and limited upside to target

Netflix ran up to a new all time high yesterday on news of expanding into Latin America and Carribean. As such they confirmed what had been expected since earlier this year - that the most likely region for international expansion would be be Latin America. This is believed to be a very attractive market of broadband subscribers with expanding wealth due to less competition than in Europe or the UK. Netflix will offer its streaming-only subscription plan into 43 Latin American and Carribean countries during 2H11.

Merriman estimates that there are more than 40M broadband subscribers throughout Latin America and the Carribean, and given the 4% broadband subscriber penetration already achieved in Canada during the first 9 months, they see 5-10% penetration rate within the new regions during the first year. This would yield 1.9-3.8M subscribers and $180-360M in annual revenues(assuming $8.00/month subscription price).

Netflix seen to be entering a period of restrained operating margins. Although on the Q1 conference management increased their anticipated 2H11 operating losses from this year's international launch to $50-70M from $50M, the analyst believes the projected Y/Y declines in operating margins for at least the next year could begin to negatively impact investor perceptions of growth trends and appropriate valuation multiples.

Company could see increased international spend guidance as management has already increased the anticipated operating loss range with a likely desire to lock-up key content to gain a head-start over potential competition it would not be surprising if management increased the operating loss guidance again. While this decision would be positive for Netflix's long-term growth prospects, the analyst believes it would cause a near term shock to current earnings estimates and the valuation multiple.

Merriman's current valuation range of $300-330 is based on a P/E multiple of 45-50x FY12 EPS estimate (or a 1.0x PEG ratio). After the 89% increase in NFLX shares since their upgrade they now see less than 10% potential upside to the target valuation range. The analysts upgrade was based on the prospects of international expansion, which has now played out.

The analyst is recommending swapping into CSTR as a play on the ongoing transition within the physical home video segment along with a wild card on the pending announcement around Redbox's digital strategy and partner. He recently boosted the EBITDA estimates above guidance and consensus following a thourough analysis of 2011 DVD rental potential and he sees additional quarters of revenue/EPS upside near-term. Using a very conservative 5.5-6.0x FY12 EBITDA estimate multiple he believes CSTR shares can reach a valuation range of $72-79 (27-40% upside).

Notablecalls: You probably won't believe this but Merriman can actually move this name. Merriman had the Street high $300-$330 valuation range when the stock was in the low $200's.

What I like about this call is that it isn't too pushy. The analyst has been right but he is now becoming more hesitant regarding the upside. Tough yoy compares coupled with high valuation is not the best combo for a mo-mo stock.

Lots of trapped shorts there but the stock should come down on this. I'm thinking 285-280 range in the n-t.

This is the last thing people expect it to do, right?

Right?

Thursday, June 30, 2011

First Solar (NASDAQ:FSLR): Home run on loan guarantees - Credit Suisse

The call of the day comes from Credit Suisse Solar team as they comment on First Solar (NASDAQ:FSLR) following an Associated Press report saying the company has won conditional loan guarantees for 3 of their Solar projects.

Here's the link: APNewsbreak: Solar loan guarantees announced

- CSFB is raising their CY11 EPS from $9.00 to $9.68; CY12 EPS goes from $9.92 to $14.03; their CY13 EPS goes from $8 to $12.62; CY14 goes from $3.70 to $9.29.

These are all hefty raises, now way above consensus.

- CSFB is raising their target on FSLR to $135 (prev. $100) noting the stock could over shoot to the $140-$150 level today to reflect longevity of earnings through 2013.

Here are some of the details:

Bottomline – raising estimates and target price. FSLR already had the Agua Caliente conditional loan guarantee in the bag, and had loaded the bases by submitting additional loan guarantees on three other projects to the DOE. Now the company has literally knocked the ball out of the park – with the Associated Press reporting that the DOE is expected to announce on Thursday that $4.5bb in additional conditional guarantees will be issued for FSLR projects.

Details: 1) $680mm for AV solar ranch; 2) $1.88bb for Desert Sunlight; 3) $1.93bb for Topaz. We had noted in several notes in the past, including most recently on Monday, that all three were in the running for a loan guarantee and the DOE had recently likely concluded the credit review of these projects. We had also noted that this week would be crunch time for additional loan guarantees. We were modeling FSLR will get one additional guarantee, but had noted all three projects were in the running. Getting all three additional guarantees is a positive surprise to our expectations, and we are therefore raising our estimates and target price.

The additional longevity of earnings at this high level is a key change in the equation – which could result in the stock trading up to $140-$150 levels. We are therefore using a simple DCF now to arrive at a new price target of $135 on the stock. Eventually the bear thesis will need to revert back to oversupply such that the panel business possibly loses money due to competition – but this is an issue the market may not focus on in the very near term.

Notablecalls: This is easily the most significant piece of Solar news this summer. These FSLR contracts were signed around 2008, which means the terms are very favourable in terms of pricing vs. today. The DOE loan guarantees provide very cheap financing, which further amplifies the profitability of the projects. The upside could be $5-6 in EPS in 2012/13.

Most analysts were expecting 1 or 2 of the projects to get DOE backing but NONE expected a slam-dunk (all 3) decision we got today.

Solar has been extremely out-of-favour sector evidenced by the whopping 46% short interest in FSLR. I would call this an explosive combo.

I expect FSLR to trade $140-145 range today. Yes, I'm expecting a $10-15 pt move.

Wednesday, June 29, 2011

U.S. Steel (NYSE:X): Deutsche upgrades to Buy; Goldman calls bottom in space

Steel stocks are getting very supportive comments from two tier-1 firms this morning:

- Deutsche Bank is upgrading both U.S. Steel (NYSE:X) and AK Steel (NYSE:AKS) to Buy from Hold with $56 & $17.50 price targets respectively.

Firm notes they could think of many appropriate titles for this report, but in a nutshell, they now view steel dynamics and investor sentiment as nearly the inverse of early 2011 when they downgraded the sector. Their upgrade is largely based on valuation, but they also believe that steel prices are nearing a 'floor'. Buy AKS and X in anticipation of steel price and demand inflection.

Steel correction healthy (necessary) and prices poised to bottom
DB says they viewed the HRC push to $900/st as negative, and reported average prices have declined to $740-750/st. Meanwhile, 'unreported' prices are below $700/st and inline with prior 'correction' expectation. They now forecast that benchmark US HRC prices will average $830/mt in ‘11 ($753/st) and $772/mt in ‘12 ($700/st); increased ~1% vs prior. Also, firm's demand outlook is unchanged as they expected NA growth of 7% and 5% in '11-‘12 and global gains of 8% and 6% respectively. Catalysts: steel prices and apparent consumption; seasonal trade could come earlier than normal

Deutsche believes that steel prices are approaching cost support (marginal cost) and could ultimately push supply out of the market. Scrap prices have been more supportive than expected in recent months and trade contacts suggest that nearterm (ex July) prices will be flat-to-up. Further, downtime announcements are likely forthcoming which they’d view as positive, if weakness persists (add’l declines of $100+/st are possible). Also, global steel prices are to become more supported including in China where they believe inventories and steel prices are near bottom. On demand, they expect the 'buyers strike' to end soon...here they find it interesting that recent conversations with consumers have focused on supply risks and when asked, most contacts recognize that end-demand remains 'ok. Also, they anticipate some improvements in industrial activity in 2H (ex. autos), and net-net, the firm thinks the seasonal steel 'trade' could begin earlier this year.

Valuation: risk-reward more favorable; AKS & X to Buy
DB notes their PTs imply average upside of 27% and steel stocks are near the low-end of trading ranges. AK Steel and US Steel shares are near levels from late ‘10 when US HRC was below $550/st. Also, their EV/t analysis shows that AKS and X are 'cheap' vs peers and historical trends, and their 'what's priced in’ analysis suggests the market is assuming below avg margins - AK appears particularly attractive using this tool. Regarding AK, the firm hasn't recommended it since early ‘10 and it has been a laggard on cost/other concerns.


- Goldman Sachs is out with a Scrap Steel sector call noting their latest channel checks indicate an upward bias (around $20 per ton) for July scrap prices, which is highly unusual considering seasonality and indeed very positive for providing cost support to steel prices. Almost all the input material costs (iron ore, coking coal and scrap) are either stable or rising going into seasonally slow summer months which underscores our view that steel prices could be close to a bottom.

Steel demand could also surprise to the upside in 3Q
Firm notes they had earlier estimated that the industry utilization rate would move close to 80% in seasonally strong spring period and then come down as we head into the summer months. Although this did not occur, they are pleased to see a steady state of demand and utilization rate hovering around 75%. Goldman believes that a typical summer slowdown in demand could be of a much lesser magnitude this year as auto industry is recovering at a rapid pace from the Japanese earthquake related supply chain disruptions.


Mini-mill margins at tipping point; steel prices should see support
Goldman notes that historically they have seen that when steel price reaches close to the cost of the lowest cost producers (mini-mills), it generally signals a bottom. And if there is some support from demand, prices generally bounce back. With expectations of busheling scrap to be around $530 per ton in July, they estimate mini-mill cost at around $680 per ton for HRC. At current level between $700 and $740 per ton, the firm sees very limited room for further degradation in steel prices. Barring any major downward correction in scrap prices in coming months, they believe that steel prices could bottom at above $700 per ton in this cycle, a very positive outcome considering that last year’s bottom was at round $540.


Notablecalls: Deutsche almost caught the recent top with their Steel sector downgrade, so with the firm now turning positive, people will likely take notice.

Regarding Goldman, this is a Scrap Steel call but as many industry watchers probably agree, scrap tends to lead the sector moves. I very much enjoyed reading their mini-mill comments.

So, with two tier-1 firms calling the bottom in Steel names, we can expect a strong upside move in the names today. The whole sector should be up.

My poison of choice is U.S. Steel (NYSE:X) which I think is the best mover in the group. I think the stock can do $45+ today.

Monday, June 27, 2011

Apple (NASDAQ:AAPL): Buy Apple for Summer Rally - Morgan Stanley

Morgan Stanley is making positive Research Tactical Idea call on Apple (NASDAQ:AAPL) this morning calling for a summer rally in the name.

- Deutsche analyst Chris Whitmore is also very positive this morning raising his #'s on AAPL.

Recent dip a buying opportunity. After meetings in Taiwan last week, they expect Apple order cuts to ease and iPhone / iPad production to begin ramping aggressively from August through year-end. Firm views the recent valuation pullback as a buying opportunity in light of the following factors, and issued a Research Tactical Idea on AAPL along with this note.

1) Post-Japan earthquake production constraints have eased, putting upward pressure on iPad shipments.

2) With improved component supply, Apple is negotiating price cuts with some suppliers, potentially boosting margins modestly in the June quarter and more in September.

3) Apple’s next iPhone will begin production in mid to late August and ramp aggressively into C4Q.

Shifting iPhone units into C4Q; CY11 estimates unchanged: To reflect a late C3Q iPhone launch, the firm shifts 2 million units from the September quarter to the December quarter but their full year estimate of 72 million units remain unchanged. An early September iPhone launch would drive upside to their lowered September quarter estimates, in their view.

Lower priced iPhones and TV are additional mid-term catalysts: Apple is forecasting a large iPhone unit increase in CY12 on the back of new products and potentially lower price points. Morgan Stanley also believes Apple is in the early design stages for a TV, which could add $19 billion and $4.50 of annual revenue and EPS longer-term.

- Deutsche Bank is also out positive on Apple this morning saying they expect the co to refresh the iPhone in September with two SKUs; namely the iPhone 5 and a lower-end iPhone 4S handset. With Nokia and RIMM struggling, the time is right for Apple to aggressively penetrate the mid range smart-phone market (i.e. $300-500 category) to dramatically expand its addressable TAM and market share.

Deutsche believes Apple could offer an unlocked iPhone 4S with a prepaid voice offering (parallels the 3G data plan vs. WiFi for iPad) which would drive significantly greater penetration into its 1.5B+ subscriber reach (2/3 are pre-paid) through 200+ carriers in 98 countries. They estimate an iPhone 4S model priced at $349 would likely be incremental to Apple’s corporate gross margin suggesting it can push down-market without negatively impacting profitability. The firm also believes near term iPhone 4 demand is tracking ahead of their previous expectation due to: the addition of 20+ new carriers in the Q, strong white iPhone uptake and wider global distribution.

Deutsche believes Apple’s international channel and related penetration opportunities are under appreciated and are raising iPhone and EPS estimates (DB at 74M iPhones in CY11 and 90M in CY12 vs. prior 71M and 85M, respectively). Although they expect Apple to move more aggressively into the midrange smartphone market, it is not currently captured in these estimates. Looking forward, they expect the upcoming iPhone / iOS upgrade and channel/carrier expansion to support strong iPhone demand over multiple quarters. Firm reiterates their Buy rating and $450 PT.

Notablecalls: It is certainly interesting to see two tier-1 firms out quite positive on Apple after a period of cautious-sounding data points. Needless to say, both are known bulls in the name.

Morgan Stanley has given their analyst teams a way to make shorter-term calls, called Research Tactical Ideas (RTI). For example, in AAPL's case they are calling for the stock to trade up in the next 60 days, giving this view a 70-80% or very likely probability of happening. That's a fairly bold statement & should generate some interest.

Also notice how the analyst is embracing the possibility of an Apple TV.

There are two interesting bits of info in the Deutsche call:

1) DBAB is calling for both unlocked iPhone 4S & a brand new iPhone 5. Lately, the consensus has shifted towards the view that there will be no lower-end iPhone. So there could be some upside there.

2) The firm is raising their iPhone ests for 2011 to 74M, which is actually above Morgan Stanley. I'm sure many of you know Morgan Stanley has been THE iPhone bull.

I think there could be some n-t upside in AAPL. RTI's usually generate immediate buy interest, so barring a market crash, the stock could be on the way up today.

I'm thinking $332+

Feedback appreciated.

Friday, June 24, 2011

United Continental (NYSE:UAL): Watch the Airlines in the n-t

I think traders should keep the Airline names on their radar this morning after United Continental (NYSE:UAL) reported weaker-than-expected RASM #'s last night.

here's the link to the PR

Here are some comments from tier-1 firms this morning:

UBS: United’s implied June revenue guidance was below expectations and when combined with other guidance suggests Q2 consensus EPS numbers are about $0.30 too high. Tomorrow will likely be a bad day for the airline stocks after a good, oil-driven day today. Given United’s June revenue, Delta’s double digit RASM growth guidance for Q2 looks very challenging.

Our 12-month PT falls to $36 from $39 based on ~6x EV/EBITDAR. Our 2011 EPS est. drops to $4.00 from $4.42. Maintains Buy.

Morgan Stanley: UAL guided to 2Q11 PRASM growth of ~8.8%, below sell-side ests. for 10%-11%. Though it was clear June PRASM growth would be lower than UAL’s ~14.5% May result, guid. implies June growth of 4%-5%, below our est. of a high-single digit result. Despite ~6pts of one-time adjustments in June, we believe UAL’s outlook will negatively impact investor sentiment as it will fuel demand risk concerns. That said, given low valuations, the recent selloff, and the demand skepticism we have heard from investors of late, we believe investors’ ests. were below the sell-side, which should dampen the neg. reaction. Furthermore, the possibility of stronger results from UAL’s legacy peers remains a potential positive catalyst.

(It's also worth noting MSCO is closing their positive Research Tactical Ideas on LCC & DAL, due to UAL news)


Barclays: June RASM from UAL was a disappointment. We underestimated revenue reconciliation payments UAL would have to make to alliance partners at quarter’s end, but we still find performance a bit disappointing. Our forward estimates reflect revenue deceleration on declining fuel and a recent softer economic climate. We now believe that deceleration developed earlier than expected, though recent feedback from DAL suggests less deceleration. We expect UAL and the group to be soft on the heels of this announcement, but at earnings multiples in the low single digits we would be buyers of material weakness, especially in UAL and DAL

Deutsche: We are lowering our June Q diluted EPS estimate for UAL from $1.75 to $1.50 (vs. consensus of $1.60) - a reversal of a change we made three weeks ago - as PRASM for the month of June came in lighter-than-expected (e.g. mid-single digit PRASM gain). We were expecting a 12% gain in PRASM for the month of June; based on quarterly guidance issued by the company last night, we estimate the gain to be closer to 5%. Also, we are lowering our full year 2011 EPS estimate from $3.35 to $3.10 (vs. consensus of $3.83).

Overall, no change to our longer-term investment case for Buy-rated UAL. Furthermore, the stock is fairly inexpensive on our more conservative forecast as its enterprise value is currently trading at 5.0x and 4.8x our 2011 and 2012 EBITDAR forecasts, respectively. As such, should the stock be under pressure this morning, we would see it as an opportunity for investors to add to their position.

Notablecalls: While not a disaster, UAL's #'s tell a story of possible deceleration in the sector. It looks like the group has been reluctant to move higher even in face of significantly declining oil price. Now that we have bad news, it appears the group is vulnerable to the downside. Analyst consensus clearly stands too high.

While total gambling on my part, it LOOKS LIKE oil is getting ready for a bounce today. That should add some fuel to the fire.

I haven't received anything from J.P Morgan's Airline God Mr. Baker this morning, so he must still be positive on the group.

I'm thinking UAL will be down 5%+ today. Maybe there's a trade there.


PS: I'm posting this on market open.

Tuesday, June 21, 2011

Advanced Micro Devices (NYSE:AMD): BREAKING NEWS - CEO FROM IBM

Advanced Micro Devices (NYSE:AMD) may have major news, possibly as soon as today:

Bright Side of News reports: The next CEO of AMD comes from IBM

Quote: While we are not in the liberty of disclosing the name of the new CEO (if the person in question signs that contract), the negotiations did not took a long time and are being finalized as I write these lines.

If the contract gets signed this or next week, expect to see the announcement coming before AMD posts its second quarter results - expected to take place on July 21, 2011 at 2PM Pacific/5PM Eastern.

Here's what the analysts have been saying past month or so:

Bernstein, June 7: This is one more potential 2H catalyst that could positively impact AMD's shares, coming on top of the launch of Llano and Bulldozer, and (hopefully) the arrival of a new CEO.

UBS, June 10: New AMD CEO has significant opportunity and challenges We believe a new CEO appointment could occur within the next 2 months, which could be a catalyst for the stock, especially given attractive valuation, as it removes a major source of ongoing uncertainty. To sustain any near-term rise, we believe the new CEO needs to tackle 7 strategic issues with servers as the most important in our opinion, followed by disciplined execution on the APU strategy. We remain Neutral given execution risks and at least until the new CEO articulates his vision.

FBR, June 16: We still have concerns about AMD’s lack of strategy (tablets and mobile) and leadership, though a new CEO hire could drive shares higher, depending upon the person. We are raising our rating on AMD from MP to OP and our target from $10 to $12, based on a higher 15x target P/ E multiple (including stock compensation, excluding net debt and interest expense).


Notablecalls: AMD stock is down 25% in the past month or so underperforming even its larger peer INTC. And now we have news out saying their new CEO is coming from IBM.

I think one couldn't ask for a better hire. IBM grooms the best of breed technology execs that can adapt to any business environment. This is what AMD needs. This is what the analysts have dreamed of.

I expect AMD to trade up markedly today, once the news gets out. AMD up 5-7%+ today? Am I too optimistic?

Monday, June 20, 2011

Home Health: Downgrading Sector View; Cutting Estimates; See More Downside - Baird

Baird's Health Care team is downgrading Home Health Sector to Underperform this morning saying they would not buy any home health stocks and expect the tape/news flow to get worse. Furthermore, 2012 estimates look to be 20%-30% too high, multiples stretched relative to the 2-3 year trading range and in general, the group looks vulnerable. Admittedly, sentiment is horrible, but we think it gets much worse before better, expect 2Q misses, lowered guidance, a very negative CMS proposal (will surprise many) and increasingly worry about the sector's exposure as a doc-fix/debt ceiling pay-for.

- AFAM cut to Underperform, $21 target (prev. $32)

- LHCG cut to Underperform, $17 target (prev. 27)

- GTIV cut to Neutral, $23 target (prev. $35)

- AMED target is cut to $26 (prev $35)


The details:

This is not a negative "call" on known issues of the F2F reg, but rather: 1) issues stemming from documentation which will lead to higher bad debt reserves, 2) we see significant risks in the upcoming CMS proposal and 3) valuations look stretched, we do not believe M&A is coming and the group is very vulnerable as doc-fix/debt ceiling pay-for.

Street too complacent on 2012 CMS proposal. We are struck with the large number of investors who do not see the risks to the 2012 coding creep. Our DC lobby contacts struggle to see any scenario in which the -3.79% coding creep does not grow and/or potentially point to future reductions. CMS will absolutely consider 2009 "coding" in the 2012 rule. Both our outside consultant and the industry's lobby believe CMS has identified ~3.3% of "increased coding" from 2008-2009. Thus, if CMS does not spread out cuts ('11 reg said they wouldn't), we could easily see a ~7% case-mix adjustment. Our revised 2012 numbers assume a 5% rate cut, which we believe is not aggressive.

Based on our recent conversations with many private companies and industry contacts, we believe the industry on average is struggling to obtain proper documentation for approximately 10%-25% (in some cases much more depending on what month) of home health SOCs (starts-of-care; e.g., admissions). Ironically, the Street has obsessed about the "volume" impact from patients that potentially would not meet the 90 days prior to or 30 days after rule, but based on multiple conversations with our network of industry participants, we have uncovered a substantial problem in obtaining the "proper" documentation from patients that actually meet the 5 requirements of the reg. As a result, we understand some providers may book ~100 bps of additional bad debt expense to account for the uncertainties related to obtaining F2F documentation for these patients (i.e., the "collectability" of these revenues). We do not believe investors are aware of this issue and it could pressure 2Q and 2H11 results.

Lowering estimates, group looks vulnerable. Our 2012 EPS estimates are now 20%-30% below the Street. We firmly believe the CMS proposal surprises on the downside probably in mid-July, which is before earnings. We expect all providers to likely miss and lower not just for the F2F "volume" impact, but due to higher reserves as providers are struggling to get documentation for patients that meet the encounter requirement. Home health stocks likely oscillate near 10x earnings (we fear could be worse as HH is likely to be included in the doc-fix/debt ceiling), thus we worry about another 20%-30% sell-off in the coming months. With this research note, we are revising our sector suitability rating to Higher Risk.

Notablecalls: This is going to hurt. Looks like Baird has done some real digging and uncovered additional problems in the sector. Many of the names appear cheap on surface but if one adjusts for the new info from Baird, they suddenly don't look that cheap anymore. It's been a tainted sector for a while.

This is a fundamental call & although many of the names carry hefty short interest I expect 5-7% downside moves in LHCG & AFAM.

GTIV and AMED will also get hit but less so.

Molycorp (NYSE:MCP): Bounce?

Molycorp (NYSE:MCP) is getting bumped at two firms this morning:

- J.P. Morgan is out with a very positive note raising their estimates and price target on the Rare Earths miner. Firm's new price tag is $105 (prev. $87) to reflect the continued rise in rare earth prices and their belief that MCP can operate significantly below its planned capacity and still realize sharp increases in shareholder value.

In fact, the firm estimates MCP could operate at 50% of capacity and see current spot prices drop 40% and still generate an NPV of $105/share. They think the stock will start to move higher as four misconceptions about MCP and the sector are ultimately dispelled: 1) MCP is struggling to achieve market prices, 2) ramping production from MCP will bring on too much supply post 2014, 3) China will ultimately reverse its production and export tightening measures, and 4) new supply outside of China will chase prices and eventually bring on too much supply.

Raising EPS. JPM is raising their EPS estimates (2012 to $5.93 from $5.25, 2013 to $14.48 from $12.51, and 2014 to $27.01 from $22.45) to reflect the continued increase in rare earth prices. In just the last month, average oxide export prices are up 22% and 195% YTD. In China over the last month, average domestic oxide prices are up 81% and 472% YTD.


- Piper Jaffray is upgrading MCP to Overweight from Neutral with a $73 price target (unch) following the stock's ~40% correction since early May.

Piper believes the pullback overly discounts the risk that rare earth prices will fall precipitously – which they believe is unlikely to occur over the next 6-12 months. They maintain their $73 price target and view continued restrictive policy actions from China, positive 2Q results, and progress on the funded capital project as potential catalysts for the stock. Less conservative pricing assumptions in our model could present upside north of $100/share.

Recent pullback creates an attractive entry point. MCP remains a highly controversial stock, fueled by the sharp run-up in rare earth pricing over the past year and uncertainty around Chinese policy on quotas and tariffs. Piper fully expects rare earth prices to fall in the future as additional supply comes online – they have incorporated an average price reduction of 60% by 2013 in their model – but looking out over the next 6-12 months, they see little change to industry fundamentals. At current valuations, they believe the market is pricing in 1) more severe price cuts in the 70%+ range AND 2) no additional volume from Phase II of the company's project plan which will double production capacity in 2014. Piper believes these assumptions are overly pessimistic in at least the near term.

Near-term catalysts present potential for upside. In the next several weeks, China will unveil its quota policy for 2H11. They expect the rare earth quota level for 2H11 to be set consistent with 1H11 levels, which will continue to strain global supply. Piper believes the release of the quota policy will once again revive fears of China's restrictive policies on rare earths, which will support near-term pricing. Additionally, they believe MCP is poised to report strong 2Q results with production levels showing a healthy q/q increase and pricing expectations on Lanthanum have been set more appropriately following the 1Q confusion.

Notablecalls: I think these calls serve to push MCP higher in the n-t. The stock is down 30 pts from its highs and ripe for a nice juicy bounce.

Short interest stands at close to 20%.

I would suggest you take a look at other Rare Earths names as well, namely Avalon (AMEX:AVL) & possibly Rare Elements (AMEX:REE) as the calls are likely to create buy interest in the whole space.

I'm thinking MCP can generate 7-10% upside. Am I too optimistic?


PS: I personally think none of these analysts have any credible insight into what's really going on in China. So this is just a sentiment trade.

Wednesday, June 15, 2011

Novatel Wireless (NASDAQ:NVTL): Actionable Call Alert!

BMO Capital Markets analyst Tim Long is making a potentially a very significant call on Novatel Wireless (NASDAQ:NVTL) saying business at Verizon is accelerating markedly.

- This is likely to result in way higher-than-consensus #'s. Firm rates their Outperform rating and $12 target.

A recent round of checks on LTE MiFi sell-through at Verizon has been positive. BMO believes Novatel’s MiFi has emerged as the preferred LTE device in their checks. Verizon appears to have stopped selling CDMA modems and hotspots in all markets, and this alone should increase NVTL’s ASPs and revenues. Firm estimates that a normal handset upgrade rate woul dresult in significantly higher revenues than their above-consensus estimates. BMO estimates upgrading Verizon’s existing 6 million Mobile Broadband Subsis worth more than $1B in device revenue. They are above consensus for both3Q and 4Q as they think the Street underestimates the impact of higher ASPs,a return to a normal upgrade rate and the expanding addressable market. They also believe that embedded revenues will start ramping and that Novatel and Sierra could take 50% of the embedded laptop/netbook market.

Channel Checks
Checks with Verizon stores in several cities since the launch of the Novatel LTE MiFi in late April indicate that it is selling well. Several store reps BMO talked with discussed selling at least one MiFi per day and all reported a significant increase over prior quarters. Almost all of the store reps they talked with are pushing the Novatel MiFi over the Samsung hotspot owing to performance issues with the Samsung device, Novatel’s MiFi brand, and better form factor. These sentiments were echoed at the Verizon website where reviews of the Samsung device were overwhelming negative. Many reviewers received several replacement Samsung devices before switching to the MiFi, which they had no issues with. BMO also expects the Novatel LTE USB modem to become available in Verizon retail stores shortly, as the LTE-only LG modem has been discontinued. Previously the Novatel modem was available only on line. They believe that Verizon is upgrading existing CDMA mobile broadband customers for free, even for customers who bought a CDMA MiFi within the past several months.

VZ Revenue Assumptions Likely Conservative
BMO models Verizon’s mobile broadband subs, upgrade rate, net adds (which it recently began reporting) ASPs, market share and dongle/MiFi mix to estimate Novatel revenues at Verizon. Firm's base case assumes that net adds slow to 300,000 per quarter, upgrade rate increases to 9%, NVTL has 75% share of MBB at Verizon, MiFi is 70% of the mix, and ASPs decline by 2% per quarter. These assumptions result in 2011/2012 revenues of $348 million/$504 million, basically double the current estimates in their model of $186 million and $200 million.

Where Their Call Differs
BMO notes they are one of only two positive ratings on the stock. Firm believes their estimates are the most detailed, as we model the company at a carrier level, looking at both units and ASP. The stock has been out of favor for a while. The last major technology upgrade cycle began eight years ago, MiFi didn’t live up to the initial hype, Asian competitors took share worldwide, and Qualcomm had taken 95% of the embedded laptop business. They think that the Mobile Broadband business, while it tends to be a bit choppier than M2M, has much better leverage and better economies of scale to create value for companies that do it well.

BMO believes the Street is modeling one quarter of strength from LTE. They, however, think there will be several strong quarters. As a result, their September revenue estimate of $142 million is well above consensus of $119 million. They are also way above for 2012 revenues and earnings.

Valuation
The P/E ratio of NVTL has varied considerably owing to the inherent leverage in the model, with P/Es in excess of 70x prior to the launch of EVDO rev A. Therefore, BMO believes EV/sales is a better comparison when looking at historic valuation. BMO's $12 price target for NVTL implies a P/E of 12x their 2012 pro forma EPS estimate and an EV/Sales of about 0.5, below the 2007 ratio of 1.2.

Notablecalls: Well guys, this is potentially a game-changing call from BMO. NVTL has been left for dead as the M2M hype didn't materialize fast enough. Remember NVTL & SWIR were all the rage back in 2007.

Now 4 yrs later Verizon the nations largest wireless operator is starting to push Novatel's Mifi in a major way. It looks like only BMO has picked this up so far, offering investors a potentially huge risk/reward situation.

Even if BMO's half-right, this thing is likely 2x undervalued.

From trading perspective I've witnessed 10-20% intraday moves in NVTL in reaction to positive news. I think we may have similar potential here in the n-t.

I'm fairly sure it can do $5.50 today but I'm certainly hoping for more.

Actionable Call Alert!


PS: I'm intentionally posting this after market open (9:30 ET AM) after watching so many of the small-cap names being bid up to unhealthy levels in the pre-market.

Friday, June 10, 2011

Chelsea Therapeutics (NASDAQ:CHTP): An Orphan Likely To Be Adopted Soon; $18 target - Roth

Roth Capital's David Moskowitz, RPh. is making an interesting call on Chelsea Therapeutics (NASDAQ:CHTP) raising his target on the small-cap biotech to $18 (up from $6).

- It looks like CHTP has significant catalysts ahead.

Here are some excerpts from the call (15pg):

* Strong Buzz On Northera At the Movement Disorder Society (MDS) Conference. On Wednesday and Thursday this week, the company featured several data presentations at the MDS conference in Toronto, Canada, including posters on additional data from Northera’s 306A study, and a subset analysis of multiple systems atrophy (MSA) patients from the drug’s pivotal 301 and 302 trials. Additionally, three presentations as part of the company’s symposium on the “Treatment of NOH in Primary Autonomic Failure with Droxidopa” featured Northera and key data from the 301 and 306A studies solidifying the drug’s broad based efficacy across multiple endpoints in NOH patients, as well as its very favorable safety and tolerability profiles. Importantly, key opinion leaders in the U.S. are awaiting access to the first drug to demonstrate clinical benefits in treating patients with neurogenic orthostatic hypotension (NOH), a major issue in patients with Parkinson’s disease. In fact, Japanese physicians that already have access to the product (marketed by Dainippon Sumitomo in Japan since 1989) expressed significant interest in the new data on the drug presented by Chelsea at the conference. Despite the Northera symposium occurring on the last day of the MDS conference, the presentation room was full, and notably, there was significant activity at the company’s poster sessions the day prior. Many physicians indicated that the striking reduction in falls in Northera-treated patients is a key benefit of the drug candidate. With an estimated 1 million PD patients in the U.S. alone, and up to one-third having symptomatic NOH, we believe Northera has the ability to be a sizable product, despite the intent on initially commercializing the product in an Orphan Drug population (NOH associated with PD).

* We believe Northera’s regulatory package is compelling and supports approval in the neurogenic orthostatic hypotension (NOH) indication. CHTP is in position to gain approval as early as 1Q'12. We raise our PT on CHTP, on increased confidence in the drug’s potential for approval and market opportunity. Data from the recent MDS meeting add support to our investment conclusion.

Summary & Investment Thesis

CHTP’s lead product candidate, Northera (droxidopa), is being readied for a 3Q 2011 submission to the FDA for review, and we believe this drug offers an important benefit to patients with neurogenic orthostatic hypotension (NOH) associated with Parkinson’s Disease (PD). NOH is a disorder caused by a deficient release of norepinephrine, which leads to decreased blood pressure upon standing, lightheadedness, dizziness, blurred vision, and syncope (fainting). In many cases, patients that have NOH can fall and worsen their health status, and in some patients, the disease itself is so debilitating that those patients remain bedridden. As a result, the FDA deems NOH an unmet medical need, and has also granted the company Orphan Drug designation for Northera. As a result, the likelihood of a Priority Review by U.S. regulators could result in a potential FDA approval of the drug in 1Q 2012. We believe the company’s clinical data package for Northera is very strong, given one highly statistically significant Phase III trial (conducted under an SPA), and another Phase III trial that provides highly consistent support to results from the larger study. Because the second study did not achieve statistical significance on the primary endpoint, many investors have exited the shares since the early part of this year, creating an opportunity, in our view. After analyzing the trial data, we believe the second study demonstrates strong efficacy of the drug, given the statistically significant result on the same endpoint as in the first trial (although not prospectively designed as the primary endpoint). Importantly, when pooling the two Phase III trials together (which we believe the FDA will do), the statistical power increases dramatically, and causes the full data set to become highly statistically significant. The compelling Phase III data, the vast efficacy and safety database generated on Northera (the drug has been on the market in Japan since 1989), as well as the high need for the drug in PD patients, boost our confidence that FDA will approve the drug next year, and that sales could peak at over $400 million in the U.S. alone. Given this potentially large opportunity, and that the company has the ability to market the drug with its own small sales force, we believe the financial leverage to the company could be impressive if Northera is approved. As a result, we believe the risk reward on shares of CHTP is compelling and we recommend that event-drive investors with a high-risk tolerance buy the stock.

Notablecalls: While I'm not familiar with CHTP story, I do like what I see so far:

- As per Roth, Docs seem to be really excited about Northera's promise. This has proven to be a significant tell in past cases.

- The company seems to be REALLY close to commercial success as approval is expected some time in 2012. They have orphan status, fast-track & a SPA. Pretty much means they will get priority review.

- Northera has been marketed in Japan since 1989, which means there's a safety database generated over 20 yrs. That resonates well with the FDA.

- There is currently only one alternative treatment on the market (and it could be pulled, according to Roth).

I'm sure there's a catch there somewhere. After all, this is a $250 million biotech. But considering Roth's target is by way the new Street high target for the name and the fact it has produced 25-50% intraday moves in the past, its worth keeping on the radar.

This one could easily trade to $5+ today.

PS: Amazingly, Roth was not involved in CHTP's last equity offering. Deutsche Bank handled the deal in Feb.

Tuesday, June 07, 2011

ARM Holdings (NASDAQ:ARMH) - Did it work?

The ARM Holdings (NASDAQ:ARMH) call begs the question - Did it work?

Well, sort of. If you look at the squeeze that happened after 9:30 AM ET it clearly didn't. Most likely one would have taken a $0.50 loss on the position.


Yet, if you look at what happened in the pre-market, depending on one's entry/exit a $0.50- 0.80 profit was to be had.

I think what one has to consider is that ARMH is an ADR (American Depository Share), which means it trades primarily elsewhere. ADR's tend to make their moves in the pre-market. There are exceptions of course, one being Nokia (NYSE:NOK). NOK tends to extend its pre-market moves in regular hours.

Just wanted to get this off my chest.

PS: Sorry for the lack of posts lately. I don't want to post stuff for the sake of posting. Posts generate traffic but as many of you know, I don't ride that way. No popularity contests here.

ARM Holdings (NASDAQ:ARMH): Intel plotting a coup at Apple? - Citi

Citigroup Semiconductor team is out with some fairly interesting comments on Apple (NASDAQ:AAPL) & Intel (NASDAQ:INTC) saying a foundry relationship may be forming between the two companies.

Firm's discussions with the hardware supply chain tend to support this belief. Intel has previously acknowledged they would be amenable to such a relationship, under the right conditions. Citi notes they suspect one such condition includes the potential for Apple to eventually convert from an ARM-based core for handsets and tablets to x86. Given the growth opportunity this opens for x86 processors, they would view such a foundry relationship, were it to happen, positively.

Potential to Migrate Apple to x86 — Intel’s revolutionary 22nm multi-gate manufacturing process is likely the main attraction for Apple. While they do expect TSMC to garner a portion of Apple’s foundry business, Intel’s substantial manufacturing lead with such a critical technology makes them a logical candidate. This is especially so given design difficulties Apple may encounter when migrating the Ax processor to 28nm and below. Citi suspects Intel’s late migration of Atom to 22nm could be in relationship to a potential foundry partnership with Apple (much like Samsung’s delay of their Hummingbird solution).

14nm the Trigger Point — Should such a deal materialize, Citi expects Intel will initially produce ARM-based solutions for Apple at 22nm. With an ARM-architect license, they see no hurdles to this. But as Intel readies 14nm (2013), potential for a shift to x86 exists. At that stage, Intel would have appropriately moved along the SOC learning curve. We believe Intel’s recent cap-ex increase, geared predominantly for 14nm, may have been inspired by the potential for an Apple relationship. Recall Intel is building a new fab in Arizona (Fab 42), geared specifically for 14nm.


- ... the note goes on discussing GM impact and current trends. Yada-yada.

Notablecalls: Nothing new about the AAPL/INTC foundy talk. This has been around for a while now. What's significant are the comments regarding AAPL converting their ARM-based core for handsets and tablets to x86.

That would present a major blow for ARM Holdings (NASDAQ:AMRH). The stock is trading up in the pre market (trades primarly in London) but as the Citi comments start circulating, I suspect we will see some selling pressure in the name today.

Thursday, June 02, 2011

Chipotle Mexican Grill (NYSE:CMG): A $1,000+ Stock? - Janney

Janney is making Glory Hound call on Chipotle Mexican Grill (NYSE:CMG) calling it a $1,000+ stock in the long-run.

(Got your attention, didn't I?)

Well, their actual 12-month target is a mere Street high of $375 (prev. $330) as their estimates for 2011/12 move above consensus.

The details:

Based on favorable feedback from multiple industry sources, we raise our 2011 and 2012 EPS estimates for Chipotle Mexican Grill (CMG $289.54; Buy) by nine cents and 35 cents, respectively, to $6.85 and $8.45. Each of these figures lies four cents above First Call consensus.

Looking specifically at Q2 2011, we take up our same-store sales forecast to 8.5% from 6.5%, above the Consensus Metrix figure of 7.8%. This drives our Q2 EPS estimate upwards by two cents, to $1.72 (four cents above First Call consensus).

Over time, we view the long-term potential of the Chipotle concept as 3,000-4,000 in the U.S., at least 2,400 in Europe, and at least several hundred in the Asia/Pacific region. This is at least 6,000 worldwide outlets for the Chipotle concept. But we do not believe Chipotle views itself as “just” a burrito company. Indeed, the first of the company’s ShopHouse Southeast Asian Kitchen restaurants is scheduled to open this summer in Washington D.C. Over the long run, it’s entirely possible that the company could host 3-5 concepts under its belt -- each focused on high-quality ingredients, fine-dining cooking techniques, and speedy customer service (albeit through different cuisines).

If -- if -- Chipotle can reasonably keep up its unit growth rate by decade’s end, then the range of P/E multiples we apply to the 2020E EPS range of possibilities (from $30.00 to $45.00) is from 20x to 30x. This sensitivity analysis suggests a year-end 2020 stock price of $600 to $1,350, with the middle portion of our assumptions getting us to a year-end 2020 stock price of $788 to $1,100. Discounting the possible year-end 2020 stock price back to today at a 10.0% discount rate generates a fair value estimate today ranging from $254 to $573. This middle portion of our assumptions, discounted back at a 10.0% rate, provides us with a possible fair value estimate between $334 to $467. With this note, we officially update our fair value estimate to $375 from $330, which is in the lower half of this middle portion of our sensitivity analysis.

Fantasizing about a best-case “what if?” scenario, the table above also includes a (very) long-term unit count potential of 10,000 restaurants, generating an average $2.7 million in annual sales, and a company-level operating margin of 20.0%. This suggests a (very) long-term EPS of over $111.

Dare to dream!

Chipotle Mexican Grill remains our top restaurant-stock pick for 2011, and we reiterate our Buy rating on it.

Notablecalls: It's not every day you see such targets (even the l-t kind) coming from from a sell side shop.

Janney has played their hand in CMG pretty well, keeping their cool while others have downgraded the name due to high valuation and whatnot.

I suspect the $1,000+ target will create some excitement among investors and traders in the n-t.